Picture a first-time buyer in today’s market.
Interest rates are climbing, lenders are scrutinizing applications more tightly, and property prices keep moving upward, all at the same moment. A property strategist with ten years of experience and hundreds of clients has watched that squeeze take shape up close. Of all the routes into the market, he says, one stands out for people seeking their first foothold: buying off-the-plan, which means purchasing a new property before construction is complete.
His comparison point is the older, established home. Those properties, he notes, tend to come with concealed repair costs that quietly drain a buyer’s savings. A brand-new home secured ahead of completion, by contrast, offers financial and lifestyle advantages that an aging house usually cannot match. He groups those advantages into four areas: affordability, government support, resilience against market swings, and design built for the future.
Affordability comes first, because entry-level buyers name it as the obstacle above all others. Established homes in traditional markets often carry inflated price tags, since demand for them is Immediate, and that leaves buyers with little room to negotiate. Off-the-plan purchases relieve the pressure in several ways. Developers commonly set competitive prices at the start, because they need early sales to build momentum and finance the project. A buyer can therefore lock in a price today, no matter which direction the wider market moves afterward.
The payment structure works differently as well. No one has to produce the full purchase amount, or a large lump sum, on day one. The usual arrangement calls for a modest initial deposit, often around 10%, with the remaining balance due only when construction reaches final completion. The strategist compares that gap to a runway. Across months or even years of building, a buyer can keep saving, tighten the household budget, and strengthen their financial profile, all without mortgage repayments weighing on them from the first day. For many young professionals and families, he argues, that breathing room turns homeownership from an Impossible dream into a realistic goal.
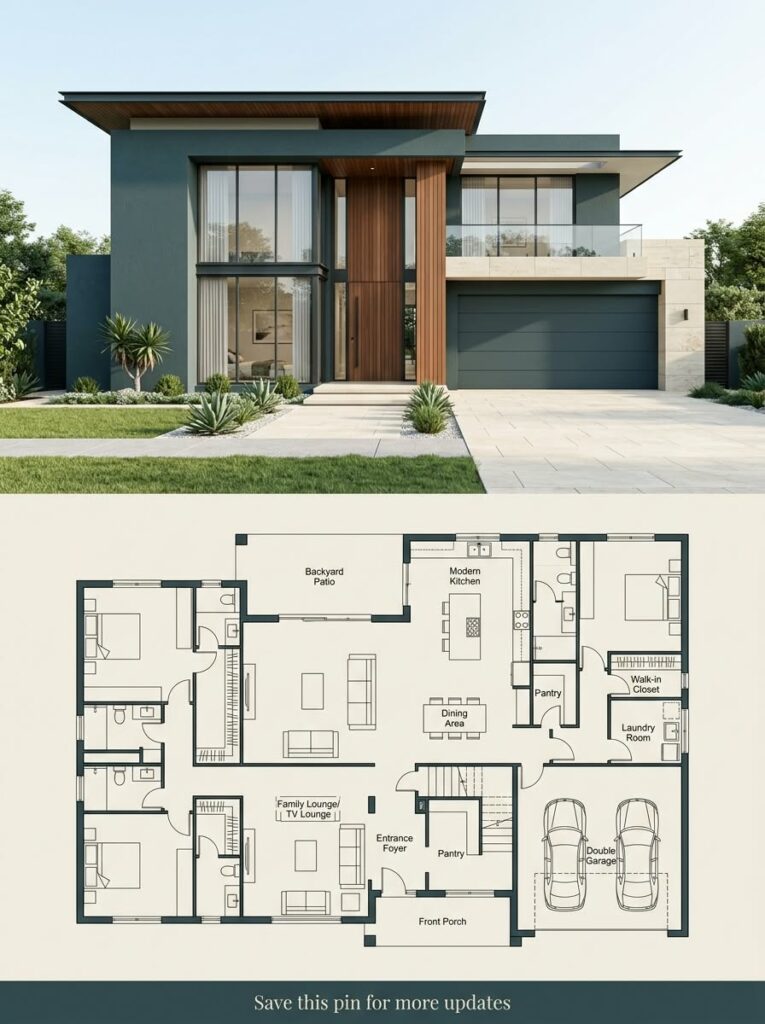
Government assistance adds a second layer. Programs exist to close the gap for first-time buyers, and while the regulatory landscape shifts often, key support systems remain active and help newcomers work around the usual barriers to owning a home. Among the most significant is the government-backed First Home Loan initiative. Banks routinely ask for a hefty 20% deposit, an amount that can take years, even a decade, of aggressive saving to accumulate. Specialized low-deposit frameworks cut that requirement sharply, in some cases to as little as 5%.
Pair a low-deposit scheme with an off-the-plan purchase, and the benefit multiplies. The buyer secures a future home at today’s fixed valuation while committing only a fraction of the capital up front. The time needed to reach the first rung of the property ladder shrinks considerably. The buyer is also shielded from two ongoing pressures: rents that keep rising and property prices that keep inflating.
Uncertainty is the third consideration, and it is built into every property cycle. Market corrections, interest rate adjustments, and sluggish economic conditions often make buyers hesitant to commit their money. The strategist points to a paradox here: that is precisely the kind of environment in which an off-the-plan purchase proves its resilience.
The mechanics explain why. When a buyer signs an off-the-plan contract, the purchase price is fixed on the first day. Settlement does not occur until construction ends, frequently 12 to 24 months later, and the market keeps changing throughout that window. If property values rise in the meantime, the buyer’s asset may already have gained equity before the keys change hands. If the market stalls for a time instead, the locked-in contract price prevents the buyer from paying an inflated peak price. That built-in buffer protects the investment and delivers a degree of long-term financial security that a traditional purchase with instant settlement cannot offer.
Money is only part of the picture, since owning a home is a deeply personal matter. Today’s buyers expect more from their living spaces than earlier generations did. They want energy efficiency, smart-home integration, minimalist aesthetics, and low-maintenance upkeep. Developers of modern off-the-plan projects understand these shifting preferences well. New developments therefore incorporate cutting-edge architectural design, double-glazing, high-grade insulation, solar power provisions, and sustainable building materials. Those features raise the quality of daily life, and they also cut ongoing utility and maintenance costs significantly.
An older established property can deliver a very different experience. Buyers often confront expensive renovations soon after moving in, unexpected plumbing failures, and costly structural upgrades. A home bought off-the-plan sidesteps those problems. It meets the latest building codes and carries comprehensive developer warranties. It also remains highly desirable to future buyers or tenants if the owner’s lifestyle needs change down the track.
Stepping into the property market for the first time is undeniably intimidating, yet the strategist maintains that choosing the right strategy changes everything. Strategic financial planning, low-deposit lending options, resilience against market swings, and the efficiency of modern architecture together form a clear and structured pathway, one that leads toward long-term wealth creation and stable housing.
In summary, the case rests on four points. A small upfront deposit and a long settlement window ease the cost of entry. Low-deposit government-backed lending shortens the road to ownership. A price fixed on day one offers protection while the market moves. And a new build brings modern design, current building standards, and developer warranties. Each point answers a different pressure on first-time buyers, and together they explain why this path deserves a serious look.
If this breakdown helped you, tap the subscribe button to keep following our coverage. Hit like so the video can reach others weighing the same decision. And switch on the notification bell, so the newest updates reach your feed the moment they go live.”