Navigating the Modern American Housing Market: Why Buying a Home is So Challenging
After spending a decade in the real estate and construction trenches, helping countless families and investors analyze property trends, one truth remains absolute: the American dream of homeownership has never felt more complex or financially daunting. Having spent ten years advising clients through shifting interest rate cycles, supply crunches, and localized economic booms, I have watched the real estate landscape transform dramatically.
Today, buyers, sellers, and industry professionals alike are grappling with a paradox. On one hand, real estate continues to serve as the bedrock of wealth accumulation in the United States. On the other hand, sky-high borrowing costs, staggering price discrepancies between states, and a severe inventory deficit have turned the simple act of buying a house into an uphill battle. To understand why homes are so expensive and hard to find, we need to peel back the layers of economics, demographic shifts, and structural housing shortages defining our current market.
The Tale of Two Markets: Extreme Price Disparities Across the U.S.
When examining the national housing market, averages can be deeply misleading. The real estate ecosystem in the U.S. is a patchwork of hyper-local economies where geography dictates everything.
Take Atherton, California, for instance. It consistently ranks as the most expensive housing market in the nation, boasting median home listing prices nearing an eye-watering $8 million. Contrast that with West Virginia, where the median home price hovers around $140,000. Interestingly, this price disparity flips homeownership rates on their head. West Virginia boasts one of the highest homeownership rates in the country at nearly 75%, while California trails behind at roughly 55%.
Nationwide, over 65% of American households own their homes, and more than a quarter of these properties are valued above a half-million dollars. For generations, property ownership has functioned as a primary vehicle for equity building. Internationally, countries like Laos and Romania boast homeownership rates exceeding 95%, reflecting different cultural and financial frameworks, but in the U.S., real estate remains the ultimate cornerstone of personal net worth.
Regional Resilience: The Michigan Housing Model
Looking closer at regional strongholds, states like Michigan showcase remarkable stability. Michigan serves as a national leader in housing tenure and ownership, with rates consistently hovering above 70% and residents often staying put in their dwellings for decades.
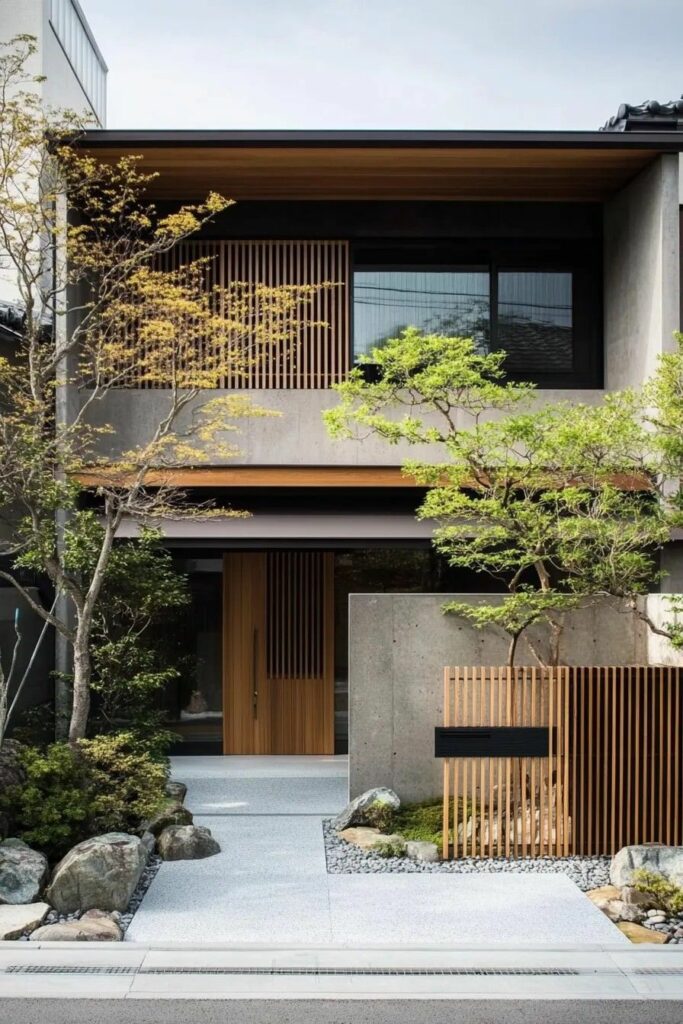
The median price of a home in Michigan sits around $250,000, representing a modest year-over-year increase of about 4%. More importantly, your purchasing power stretches significantly further here compared to coastal epicenters. While the median square footage for a home nationwide sits around 1,800 square feet, Michigan homes average over 2,000 square feet. Newly constructed properties across the country tend to be even larger—frequently exceeding 2,500 square feet—though the existing housing inventory features plenty of charming, smaller historical homes.
The Root Cause: A Staggering National Housing Shortage
Square footage and regional perks aside, the elephant in the room remains raw inventory. As of recent federal and industry tracking, the United States features roughly 150 million total housing units, with over 130 million currently occupied. However, years ago, organizations like the National Association of Home Builders warned that population growth trajectories combined with an aging housing stock would trigger a severe supply crisis.
Industry estimates currently point to a national deficit of nearly 6 million available homes. California alone bears the brunt of this shortfall with a deficit of approximately 2 million properties, while New York faces a shortage nearing 1 million homes.
Raw numbers, however, only tell half the story. Affordability acts as the ultimate gatekeeper. Even if inventory magically appeared, can first-time buyers actually afford to purchase in those high-demand states? We see localized anomalies in places like Fort Lauderdale, Florida, which some analysts view as temporarily overbuilt. There, median home prices exceed $500,000, and a substantial percentage of properties sell below their initial listing price, proving that pricing alignment is just as critical as raw construction volume. Building affordable housing tailored to the actual demographics looking to buy is the only sustainable path forward.
Pandemic Aftershocks and the “Locked-In” Rate Phenomenon
The COVID-19 pandemic permanently altered how we view living spaces. A massive segment of the workforce discovered remote capabilities, prompting lifestyle relocations. Simultaneously, however, shifting macroeconomic policies sent interest rates climbing.
This created a unique bottleneck. Millions of existing homeowners locked in historic 30-year fixed mortgage rates below 4% are heavily disincentivized to sell. Trading a low fixed rate for a higher rate on a new mortgage makes moving a financially painful proposition, keeping potential inventory tightly locked away.
Furthermore, we are witnessing a fascinating trend reversal among older American adults. For decades conventional wisdom assumed retirees would automatically flock to warm Southern states for their golden years. Many soon realized that relocation meant abandoning critical life anchors—long-standing relationships with physicians, places of worship, local community spots, and nearby family members. Consequently, more seniors are choosing to stay put, reinvesting in their current properties through remodeling projects designed to safely accommodate aging in place. From a financial and emotional standpoint, upgrading an existing home frequently makes far more sense than relocating.
The Generational Divide in Homeownership
While overall U.S. homeownership rates have held relatively steady in the mid-to-high 60% range, a stark generational divide persists. Nearly 80% of adults over the age of 65 own their homes, whereas that figure plummets to under 40% for young adults under the age of 35.
Lower fixed-rate mortgage financing will undoubtedly help level the playing field for younger buyers, but financial instruments alone cannot solve the crisis. Most regional markets desperately require a massive influx of new inventory.
As we have consistently emphasized to clients and industry peers, housing affordability is never a one-size-fits-all issue. Restrictive land availability, zoning hurdles, prime location demand, soaring development expenses, and the high cost of capital all conspire to limit housing mobility for millennials eager to plant roots and achieve homeownership.
Moving Forward
Overcoming the current housing affordability and inventory crunch requires a coordinated effort. Industry professionals, builders, local municipalities, and prospective buyers must work collaboratively to maintain our existing housing stock while aggressively streamlining the creation of new, attainable homes. Whether you are looking to purchase your first property or planning a major renovation to modernize your current space, partnering with experienced professionals is essential to navigating this complex market successfully.
Are you ready to take the next step in your real estate journey? Reach out to our team of seasoned experts today to schedule a comprehensive market consultation and discover the best strategy for your housing goals.