Handing over the keys is the final beat of a long process, and for most people it caps one of the largest financial and emotional commitments of their lives.
A deed gets recorded, a door opens, and years of planning come due.
One real estate agent, with a decade of direct work alongside buyers, has a view on how to get there with less dread. The agent’s experience includes negotiating competitive mortgage refinancing terms and tracking housing trends. Across all of it, one pattern holds: the purchase feels overwhelming up front, then becomes orderly once it is split into deliberate stages. The agent lays out a ten-step roadmap through the U.S. housing market, running from the first calculation to move-in day.
Step one comes before any listing is opened or any open house is visited. It is a hard look at your own finances. In ten years of advising clients, the agent has seen plenty of buyers fall for homes they could not truly afford. The remedy is basic math. Total your gross income, your monthly debt obligations, and your routine living costs, then use those figures to work out your debt-to-income ratio, or DTI. Lenders examine that number closely. Setting a realistic budget at the start points you toward homes with monthly mortgage payments you can carry, and it protects your financial footing over the long haul.
Step two is the down payment, which remains a cornerstone of home ownership. On a traditional conventional loan, 20% down is often considered ideal because it eliminates private mortgage insurance, or PMI. Even so, a number of programs let qualified buyers put down much less, in some cases only 3% to 5%. Your personal savings are not the lone source of funds. First-time home buyer assistance programs, down payment grants, and employer-sponsored housing benefits can all help you reach the target faster.
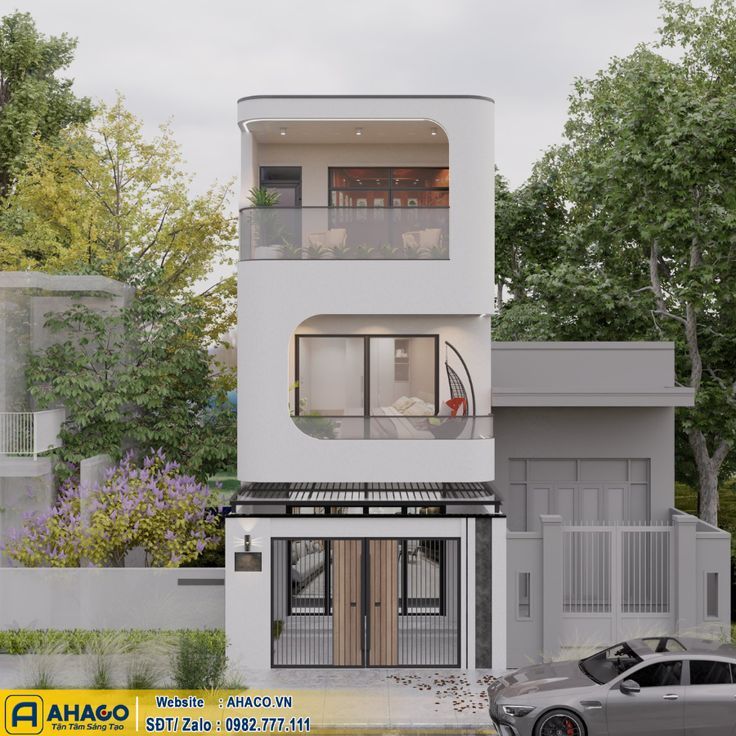
Step three is learning the local landscape. Real estate is hyper-local, but informed and profitable decisions still depend on understanding the wider housing market. Examine individual neighborhoods and follow property price trends, past and present. Check for municipal or commercial projects planned nearby that might influence future appreciation. Awareness of inventory levels and of local supply and demand also gives you firmer footing at the negotiating table once you are ready to move.
Step four is mortgage pre-approval, and the timing should be early. Never go looking at property without a pre-approval letter. The letter tells sellers and listing agents that you are a serious, qualified buyer with financing within reach. Compare interest rates, loan origination fees, and closing costs from multiple lenders, including credit unions, national banks, and digital mortgage brokers. A good mortgage loan officer can save you thousands of dollars across the life of the loan.
Once the budget and pre-approval are in place, step five is deciding what your future home has to offer. Sort the essential “must-haves” from the flexible “nice-to-haves.” Consider key factors such as school district ratings, commute times to work, neighborhood safety, square footage, architectural layout, and features like a fenced backyard or a garage. Ranking these priorities keeps the search efficient and on target.
Step six is the hunt itself. With a clear picture of what you want and financing secured, begin touring properties in earnest. Use leading real estate platforms, book private showings, and go to open houses. A seasoned buyer’s agent can provide access to off-market listings and add useful local knowledge. Keep detailed notes, shoot video during walkthroughs, and judge each property objectively against the criteria you set earlier.
When the right property appears, step seven begins: making the offer. Your real estate agent helps you prepare a compelling purchase and sale agreement, which spells out the proposed purchase price, the earnest money deposit, contingency deadlines, and the target closing date. In competitive markets, an offer may need strategic clauses or escalation addenda. After the seller accepts and signs, the contract is binding, and a qualified real estate attorney should review it Immediately.
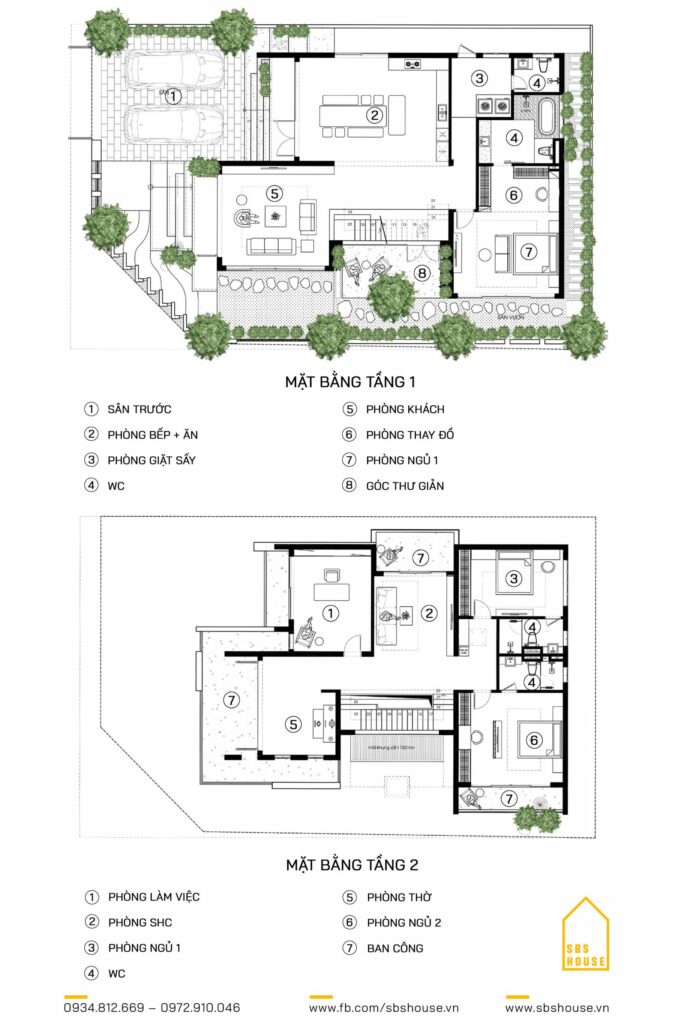
Step eight is due diligence, your primary protection against unexpected financial liabilities. Bring in a licensed home inspector to assess the structural integrity, roof condition, plumbing, electrical systems, and HVAC units. Go through the title search report, the HOA covenants where they apply, and the environmental disclosures. Whatever problems surface during this contingency period give you leverage to negotiate repair credits or price reductions before you commit.
In step nine, the due diligence contingencies are cleared, and your lender advances the loan file from conditional approval to final underwriting. Deliver requested paperwork quickly, such as updated bank statements or employment verifications, so the closing schedule stays intact. Lock in your interest rate if you have not yet done so. Review your Closing Disclosure, or CD, with care and confirm the final cash-to-close amounts.
The tenth and final step is closing day. You sign the last loan documents and legal paperwork, wire your closing funds, and complete the official transfer of ownership. When the deed is recorded at the county office, the keys to your new property belong to you. Becoming a homeowner is a remarkable achievement, and it merits a moment of celebration as you step through the door.
Every step builds on the one before it, from an honest accounting of your finances to the recorded deed and the handing over of the keys. That progression is what makes a daunting purchase manageable. It also leaves a question worth carrying into your own search: which of these ten steps are you ready to start on today?
If this roadmap helped you, hit the subscribe button and give the video a like. Turn on the notification bell too, so you catch our latest stories the moment they go live.”