Three advantages sit at the center of the off-the-plan case: a smaller deposit, a delayed settlement, and a home built to current standards.
Each one moves the buyer toward the same result, which is owning a home sooner and from a steadier financial position.
Pressure on first-time buyers is real. Economic volatility, rising interest rates, and affordability barriers have converged, and none of them is showing signs of letting up. The author of this report has spent a decade working closely with property buyers, developers, and real estate financiers, and has watched market cycles shift sharply over that time. For anyone trying to reach the first rung of the property ladder, the climb looks steep. Buyers who understand today’s market dynamics, financial products, and government schemes, though, can turn a hard market into a rare opening. Purchasing a home before a single wall has gone up unsettles many first-time buyers, yet the route offers benefits that the traditional market seldom matches.
Start with the picture most people hold of buying a home. They see themselves walking through a finished house, opening kitchen cabinets, and choosing a spot for the sofa. Established homes in prime areas, however, often carry steep prices driven by Immediate demand, and many need costly maintenance or renovation from the first day of ownership.
An off-the-plan purchase works differently. It is a contract to buy a residential property that is not yet finished, signed either before construction begins or while the build is underway. The buyer locks in the contract now and pays the settlement later, rather than fighting through fierce bidding wars over established dwellings. That structure gives today’s buyers a forward-looking way into the market.
The deposit is where the difference shows most clearly. Traditional lenders usually ask for 20%, and for a renter that figure is often the first real obstacle to ownership. Saving that much can take years of discipline. For eligible new builds and off-the-plan purchases, targeted assistance programs can reduce the requirement to as little as 5%. The First Home Loan scheme is one such program, and for qualified applicants it can shorten the road to ownership considerably. The gap between 20% and 5% helps explain why a growing number of savvy buyers are choosing off-the-plan.
The delayed settlement carries equal weight, since housing affordability remains one of the most pressing hurdles buyers face. A household that saves for a large deposit while paying high rent can end up stuck in limbo. Off-the-plan properties ease that squeeze through structured payment terms. Typically, the buyer pays a modest initial deposit, often held securely in a stakeholder trust account, and owes the remaining balance only at practical completion. That leaves months, or even years, to keep building savings. Daily financial stress eases, and ownership becomes far more attainable. Developers also tend to price early-release units competitively to generate initial momentum for a project, which means astute buyers can acquire brand-new real estate below later market valuations.
Buyers do not have to plan their finances alone. Government support mechanisms continue to play a pivotal role in easing the transition into homeownership. Programs such as the First Home Loan scheme lower the barrier to entry and let buyers get in much sooner. Reaching the property ladder years earlier means building equity and benefiting from long-term capital appreciation. The alternative is to keep paying surging rental rates that build someone else’s wealth.
Timing within the market cycle also works in favor of this approach. Property markets are cyclical by nature, moving through periods of growth, stabilization, and correction, and one of the strongest arguments for off-the-plan properties is the resilience they offer during economic transitions. A buyer who purchases off-the-plan fixes the price at today’s valuation but does not settle until construction ends, and that gap creates a distinctive financial buffer. If market values climb while the building rises, equity grows before the buyer ever moves in. Even when the market is sluggish or flat, buying new secures a fixed price today. That protects the buyer from inflationary construction cost pressures, which typically push up the price of future builds. Over a medium-to-long-term horizon, real estate consistently rewards patience, and brand-new assets have historically commanded stronger capital growth and higher rental yields if they are later converted into investments.
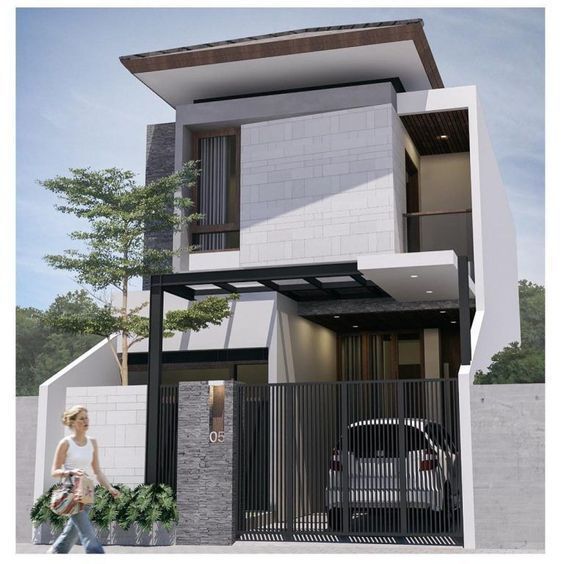
Homeowner expectations have also shifted considerably. Today’s buyers prioritize energy efficiency, sustainable building materials, smart home integration, and functional architectural layouts that accommodate remote work and flexible lifestyles. Established properties often need expensive retrofits to meet those contemporary standards. Off-the-plan properties are deliberately designed with future trends in mind. Reputable developers build advanced insulation, double glazing, energy-efficient heat pumps, and sustainable materials into their blueprints. Investing in a new build therefore effectively future-proofs the asset, and these modern amenities keep a home highly desirable, energy-efficient, and competitive in both rental and resale markets for decades to come.
Buying real estate is more than a transaction. It is the cornerstone of long-term personal wealth and housing security. Market fluctuations and economic headlines can breed hesitation, but strategic planning is what separates successful property owners from perpetual renters. Off-the-plan purchases combine accessibility, modern living, financial flexibility, and growth potential. With lower initial deposits, government support frameworks, and future-proofed architectural designs, aspiring homeowners can sidestep the traditional roadblocks of the market. Those ready to take control of their housing future, and to see how off-the-plan opportunities could fit their specific financial situation, can reach out to the property advisory team to schedule a personalized strategy consultation.
Taken together, a lower deposit, a later settlement, and a home designed for the decades ahead make up the core of the argument. For buyers weighing their options, the question worth carrying forward is which of those three advantages matters most to their own situation.
If this report gave you something useful, hit subscribe so the next one lands right in your feed. Tap like to let us know it helped, and switch on the notification bell so the latest news reaches you the moment it breaks.”