A real estate professional with ten years of experience guiding clients through purchases has built a plan for people buying their first property.
He has seen newcomers to the market move from giddy excitement to outright panic, and he describes the experience as feeling your way through a maze with the lights off. His approach breaks the process into ten strategic phases, from a budget check to the moment the deed transfers. Done in order, it removes the guesswork, protects hard-earned savings, and positions a buyer to secure the best mortgage rates available today.
The plan begins before any online listing is opened or any suburb visited. Stage one is an honest audit of your own finances. In his professional judgment, your debt-to-income ratio is the foundation of a successful purchase. Add up your steady income, track your monthly spending, and list every existing obligation, including student loans and car payments. A preliminary financial review, or a conversation with a trusted lender, will reveal a realistic budget ceiling. Learning those numbers early prevents disappointment later and keeps your search on homes that fit your lifestyle without straining your finances.
Stage two is the down payment, the steepest hurdle for many first-time buyers. Lenders have long favored 20% down because it avoids private mortgage insurance, known as PMI. Lending today is more flexible, however. Depending on your financial profile and on government-backed assistance programs, you may qualify for low-down-payment loans requiring only 3% to 5% down. To build the fund faster, set up automatic savings early and cut unnecessary discretionary spending. Eligible buyers can also consider specialized savings vehicles or retirement account withdrawals.
Stage three is market research. Real estate is hyper-local, and conditions can differ sharply between neighborhoods. Careful study helps you identify undervalued communities, compare recent sales, and anticipate municipal developments that could push property values sharply higher. Look at average days on market, historical appreciation rates, and school district ratings. Knowing local pricing trends also gives you leverage once negotiations begin.
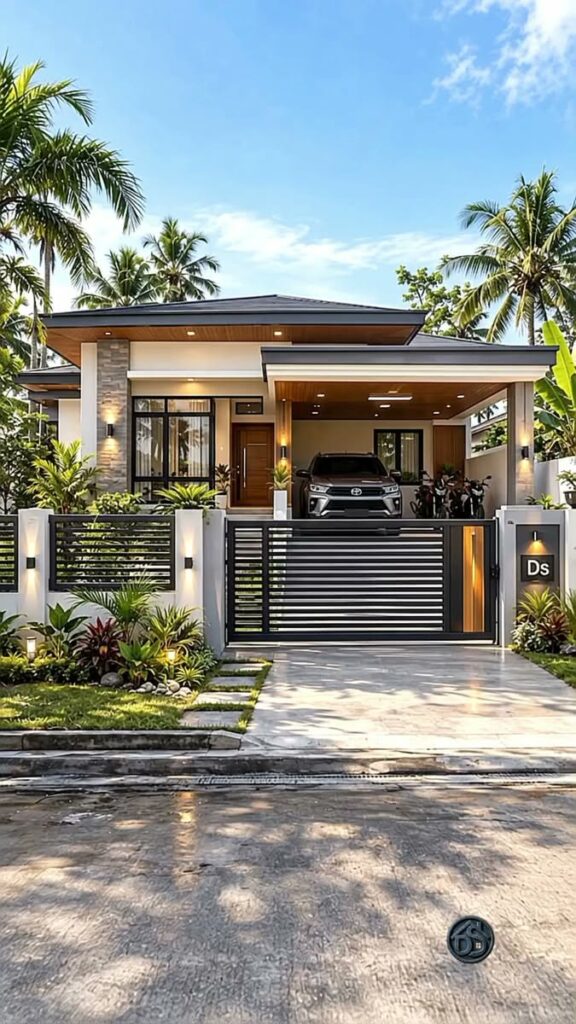
Stage four, mortgage pre-approval, should also happen early. Searching for a house without it is like walking into a high-stakes auction without a paddle. A formal pre-approval letter fixes your exact buying power and tells sellers and real estate agents that you are a serious, qualified buyer ready to transact. Use this window to shop among multiple banks, credit unions, and independent mortgage brokers. Compare mortgage refinance options, fixed-rate loans, and adjustable-rate mortgages so you can lock in the lowest interest rate and the most favorable terms for your long-term financial security.
Stage five also comes before any tour: deciding what you truly need in a home. Open houses are full of distractions, from luxury staging and granite countertops to sprawling backyards. To stay grounded, write a clear list that separates absolute must-haves from flexible nice-to-haves. Weigh the key variables, including geographic location, commute time to work, proximity to reputable schools, structural layout, and the number of bedrooms and bathrooms. Settling these criteria in advance keeps the hunt focused and efficient, and keeps the result aligned with your future lifestyle goals.
Stage six is the search itself. With a pre-approval letter and a wishlist in hand, you are ready to tour homes. Use online real estate platforms, attend weekend open houses, and partner with an experienced buyer’s agent who knows your target neighborhood well. A seasoned agent can catch red flags you might overlook, give you early access to new inventory, and arrange private viewings around your busy calendar. At every property, take notes and photos so your Impressions stay organized.
Stage seven begins once a single home meets every requirement. Your agent helps you draft a competitive offer, and this phase involves strategic negotiation over price, closing timelines, repair concessions, and contingencies. When the seller accepts the offer and signs the purchase agreement, you are officially under contract. Bring in a qualified real estate attorney or a title company right away. They will review all legal disclosures, covenants, and contract terms to protect your interests.
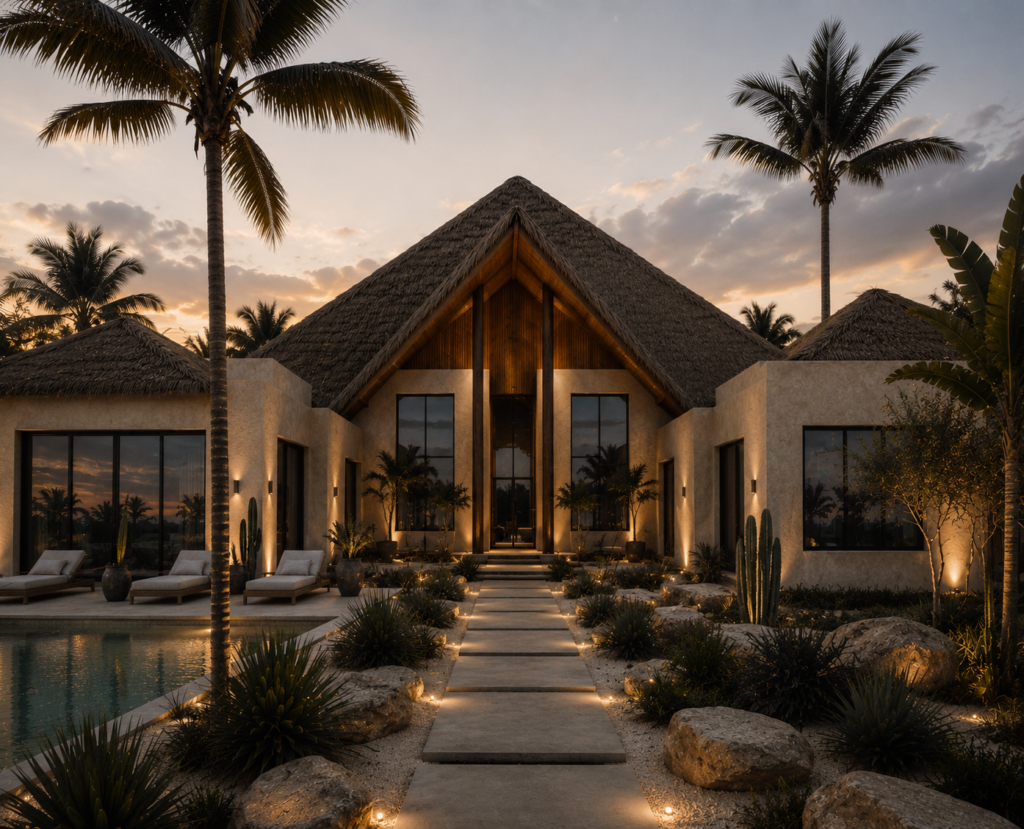
Stage eight is due diligence, and entering escrow does not mean the race is won. Hire a certified home inspector to evaluate the property’s structural integrity, roof condition, plumbing, electrical grid, and HVAC systems. At the same time, work through municipal zoning documents, title searches, and property history reports. If the inspection reveals major defects, you keep the legal right to renegotiate the price, ask the seller to pay for repairs, or walk away with your earnest money deposit intact.
Stage nine starts when due diligence is cleared and your lender moves your mortgage file into final underwriting. Respond quickly whenever you are asked for updated financial information, tax documents, or employment verification. Lock in your interest rate, confirm the loan amount, and read the final closing disclosure statement line by line. Check the closing costs, insurance premiums, and escrow fees. Once you understand every dollar you are committing, nothing unpleasant can surprise you at the closing table.
Stage ten, the last, is settlement day. You sign the final transfer documents, pay the remaining closing funds, and watch the property deed pass officially into your name. Once the transaction is recorded with the local county, the keys to your new front door are yours. Take a moment to mark the milestone before you begin coordinating the move.
Each of these ten stages, from assessing your finances to collecting the keys, guards against the costly errors that trip up unprepared buyers. Taken in order, they turn a daunting process into a path you can walk with confidence. What looks like a maze at the start becomes a series of decisions made one at a time.
If this breakdown gave you a clearer picture of the road ahead, hit the subscribe button so the next video lands in your feed as soon as it’s out. A quick like helps other future homebuyers find it, and turning on the notification bell means the latest updates reach you first.”