Ten steps stand between a first-time buyer and the keys to a first home.
They come from a real estate professional with a decade in the industry, who has walked a great many clients through the process. Followed in sequence, the steps move a hopeful buyer to ownership without putting personal finances in danger. From the base, homeownership can look like a mountain, but divided into stages it becomes a climb a buyer can manage.
The work starts at the kitchen table, well before any listing site is opened. A buyer should add up monthly income, then fixed costs and discretionary spending, then every debt already owed. Lenders weigh the debt-to-income ratio heavily when setting a loan amount. Drawing up a rough budget early also prevents a buyer from becoming “house poor,” and it keeps spending at a level that stays comfortable over time.
Next is the down payment, which for many first-time buyers is the steepest hurdle. Conventional lenders usually prefer a 20% down payment because it avoids private mortgage insurance. Yet several assistance programs for low down payments allow qualified buyers to close with far less cash at the start. Buyers who want to save faster can set up automatic contributions early, ask whether an employer matches savings, or look into government-backed housing grants.
Third, a buyer needs to understand the local market, since that knowledge is what makes confident investing possible. That means studying how fast prices have risen in the neighborhoods of interest and comparing past sale prices. It also means learning about zoning changes or infrastructure projects on the horizon that could push property values up. A buyer who knows an area in detail negotiates from a stronger position and can spot overlooked properties before competing buyers do.
The fourth step is a mortgage pre-approval letter, and the professional advises against touring any home before holding one. The letter sets out the exact amount a buyer can spend. It also tells sellers that a qualified, serious buyer is prepared to close. Buyers should compare multiple lenders, paying attention to competitive interest rates, low origination fees, and loan products built for first-time buyers.
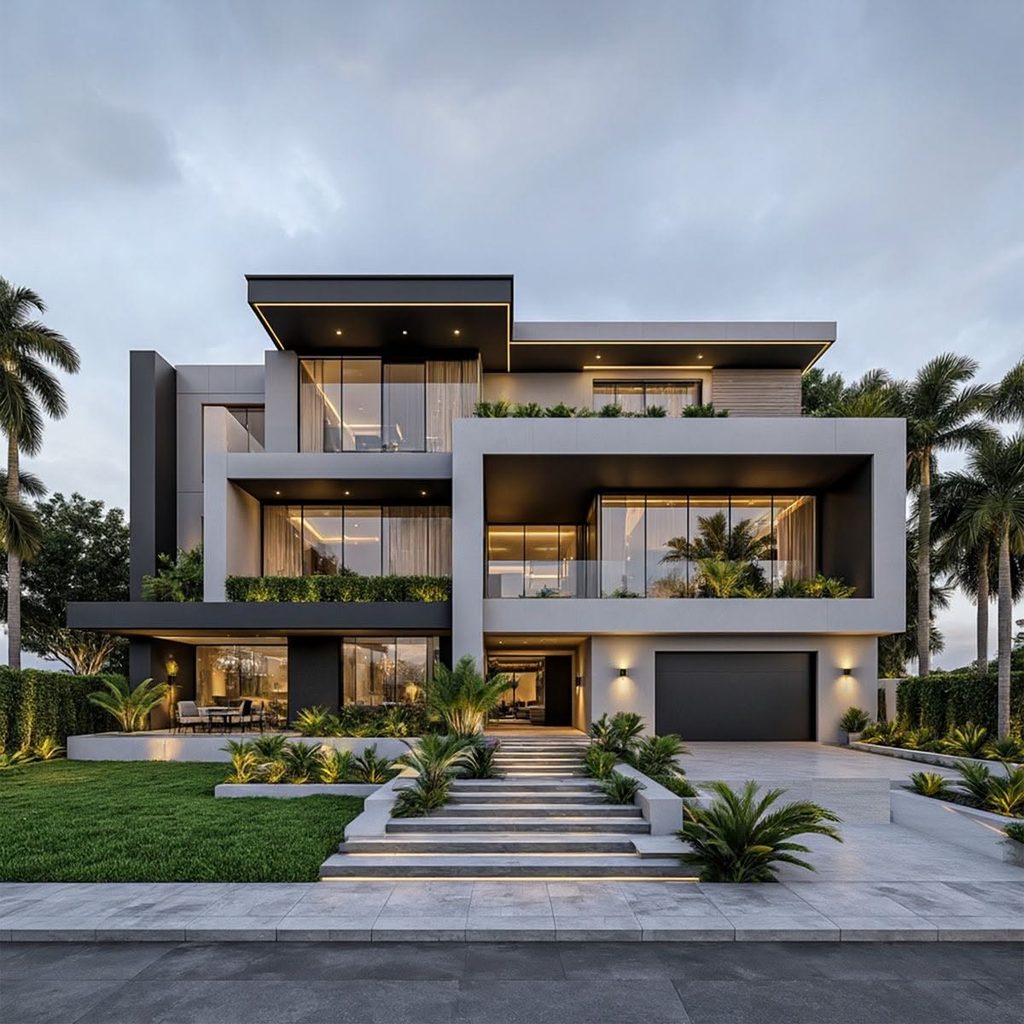
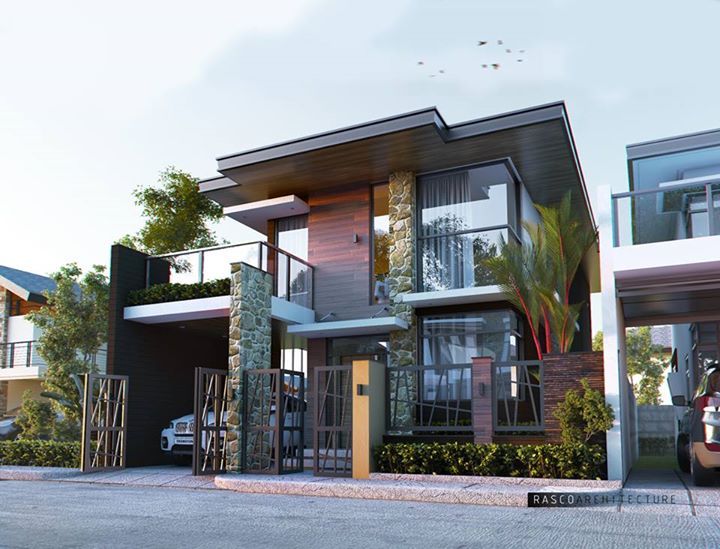
Fifth, the buyer ranks what matters in the home itself. Staged luxury furnishings and oversized kitchens are easy to fall for, so the professional suggests splitting a list into absolute must-haves and features that would simply be nice. The evaluation should cover commute times, school district ratings, property tax rates, square footage, and structural layout. An organized list of priorities keeps the search focused and efficient.
The sixth step, active house hunting, begins once the pre-approval letter is in hand and the criteria are settled. Buyers can browse the leading online real estate portals, visit open houses on weekends, and work with an experienced buyer’s agent who knows the local sub-markets thoroughly. A capable agent can offer early access to listings and help determine whether an asking price reflects current market conditions.
When the right property appears, the seventh step is the purchase offer, which the buyer drafts together with the agent. This stage covers strategic pricing, negotiation over the earnest money deposit, and contingencies that safeguard the buyer’s interests. After the seller accepts the terms, both parties sign a purchase and sale agreement, and a real estate attorney should review it right away.
Due diligence and inspection make up the eighth step. An accepted contract only opens the verification phase. A certified home inspector should check for structural defects, roof wear, plumbing problems, and electrical hazards. Meanwhile, the buyer reviews title commitments, neighborhood restrictions, and municipal zoning reports, so that no legal surprises come attached to the property.
The ninth step is finalizing the financing. Once due diligence is cleared, the buyer turns the pre-approval into a binding loan commitment. This involves settling on the loan amount, choosing between a fixed and an adjustable interest rate, and locking in that rate to guard against market volatility. Before signing the final documents, the buyer should read the closing disclosure carefully and confirm every fee, the closing costs, and the monthly payment obligations.
Settlement day is the tenth and last step, the culmination of the entire journey. At the closing meeting, the buyer signs the final mortgage documents, transfers the down payment and closing costs, and pays the remaining balance. When the deed is officially recorded, the keys to the new property are handed over, and the buyer can start moving in.
The professional’s conclusion is that solid preparation and expert guidance take much of the fear out of a first purchase. Working through each milestone in order protects hard-earned capital and builds wealth that lasts a lifetime. The original source closes with an offer: anyone wanting personalized advice for their local housing market can schedule a complimentary strategy session and start the path to homeownership.
Taken together, the ten steps form a chain in which each link depends on the one before it, from the first look at a budget to a set of keys in hand. That is why the order of the steps carries as much weight as the steps themselves.
If this walkthrough was useful, hit the subscribe button so the next video finds its way to you. Give it a like to let us know it helped, and turn on the notification bell so the latest updates reach you as soon as they go live.”