Ten years of working alongside residential buyers and developers have led the source’s author to one conclusion: off-the-plan property, meaning a home purchased before construction is finished, has become a strategic way into the housing market.
The problem it addresses is simple to state. Established houses in prime suburban pockets carry very high price tags, and strict borrowing limits plus steep upfront cash requirements lock out many would-be owners. With lending standards tight, construction costs climbing, and housing shortages persisting, savvy buyers are choosing new builds rather than joining a fierce contest for tired, existing dwellings. The author lays out several reasons this route suits people trying to get a foothold in a complicated market.
Start with the money. An off-the-plan buyer typically secures the purchase price with a relatively modest deposit, often ten percent, and the remaining balance is not due until construction is complete. Three benefits follow. First, the price is locked in today, so if values rise substantially during the build, the capital gains arrive before the buyer moves in. Second, settlement comes months or even years later, giving the buyer an extended runway to keep adding to savings, which also eases mortgage stress. Third, a brand-new home spares the owner the Immediate repair bills, roof replacements, and plumbing overhauls that often weigh on older properties. In investment terms, the buyer enters with a smaller initial footprint and spreads the financial exposure across a manageable timeline.
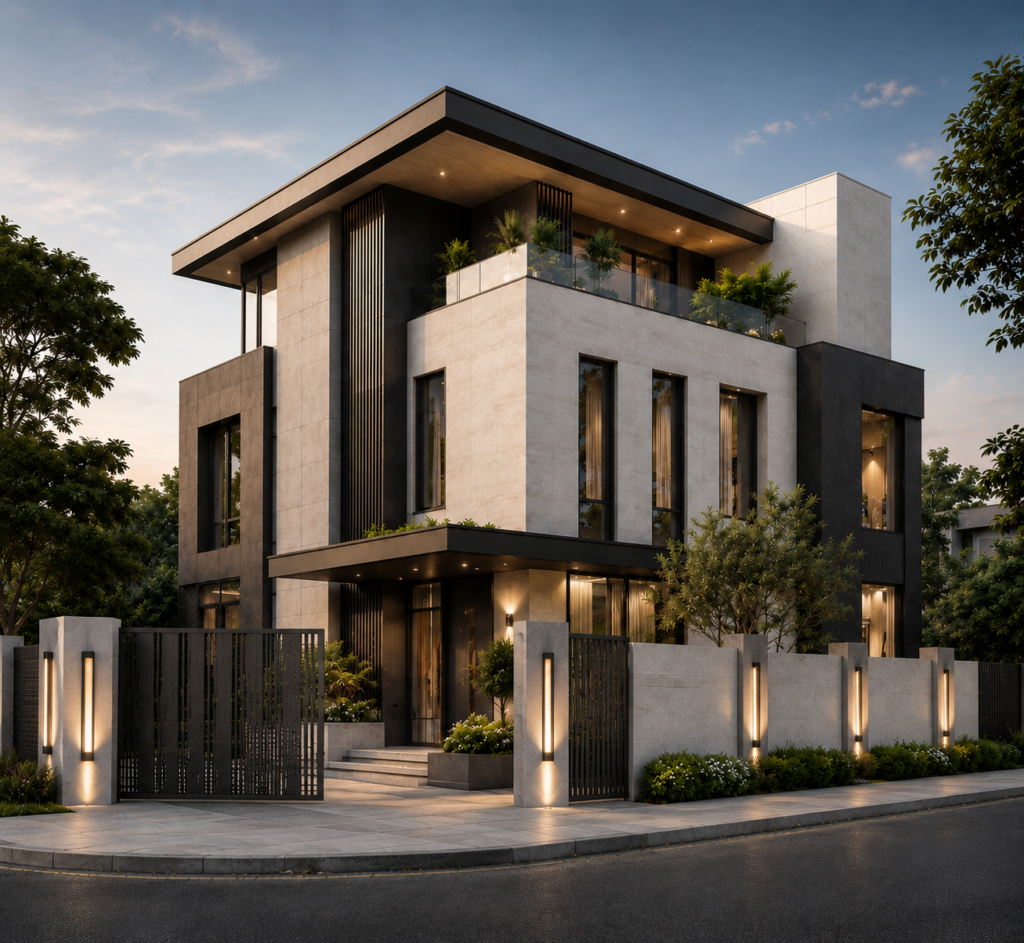
The deposit itself is the next obstacle. The traditional twenty percent is the hardest step for many buyers, and government assistance programs and specialized banking products keep evolving to support new construction. Some grants shift with economic policy, but initiatives such as the First Home Loan scheme remain vital lifelines. These government-backed programs can cut the required deposit to as low as five percent for qualifying buyers who purchase new builds or off-the-plan property. Combined with an off-the-plan purchase, that low deposit speeds things up considerably. Rather than spending five to seven years saving aggressively while property values outrun the savings rate, the buyer can commit early, secure the asset, and let time work in their favor. Lenders also tend to view financing for new builds more favorably, since modern, code-compliant dwellings carry lower Immediate risk profiles.
Timing worries buyers too. Property markets move in cycles, and slow periods or interest rate adjustments can make people hesitate for fear of buying at the peak. According to the author, an off-the-plan purchase acts as a natural hedge against short-term volatility. Construction runs anywhere from twelve to twenty-four months, so swings in the market during the build often smooth out by the time the keys change hands. If the broader market grows steadily over that stretch, the buyer’s equity position strengthens before settlement. Modern developments also tend to be master-planned communities, designed with future infrastructure, transport links, and commercial hubs in mind. Buying into one places the owner in the path of urban growth, and the writer says this ensures superior long-term capital appreciation compared with stagnant, land-locked older neighborhoods.
Expectations for the home itself have changed as well. Today’s homeowners demand more than previous generations did, and energy efficiency, smart home technology, open-plan layouts, and acoustic insulation are now expectations rather than luxuries. Older homes often need expensive retrofitting to meet contemporary energy standards. An off-the-plan home, by contrast, is guaranteed to comply with the latest building codes, insulation standards, and environmental ratings. Developers increasingly build in sustainable features such as double glazing, high-performance heat pumps, solar panel readiness, and water-efficient fixtures. Those inclusions translate directly into lower ongoing utility bills and a healthier living environment. They also line the investment up with consumer preferences that will shape market demand for decades, which keeps the asset highly liquid and attractive if the owner later decides to sell or rent it out.
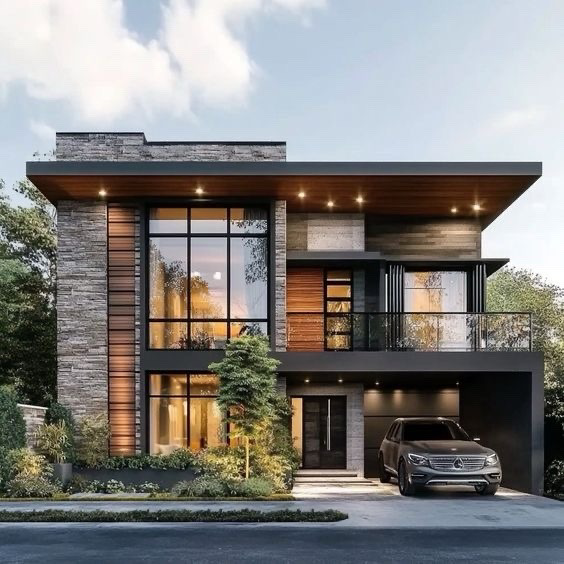
Taken together, the author argues, these points show that entering the property market need not be an overwhelming ordeal. By understanding the strategic advantages of off-the-plan property, first-time buyers can sidestep many traditional barriers, from excessive deposit requirements to costly maintenance on older homes. Low-deposit financing options, price-locking mechanisms, and modern, energy-efficient designs together offer a clear roadmap to homeownership. For anyone ready to stop renting and take control of their financial destiny, the author says, exploring off-the-plan opportunities could be the most Important decision of the year. The closing advice is to contact the author’s expert advisory team to review current developments, discuss financing eligibility, and find a property suited to long-term goals.
The trade at the heart of all this is straightforward: a smaller deposit and a locked-in price in exchange for patience while the building goes up. What the buyer gets at the end is a new, code-compliant home in a community designed around future growth. Whether that exchange makes sense remains a question each buyer must answer against their own savings, timeline, and goals.
If this breakdown was useful, hit the subscribe button so you can follow more reports like it. Give the video a like if it helped, and turn on the notification bell so the latest stories reach you the moment they go live.”