Consider what happens at the instant a buyer signs an off-the-plan contract: the purchase price is locked in.
Settlement does not arrive until construction wraps up, typically 12 to 24 months afterward. According to a property strategist with ten years in the field, that one feature of the deal underlies nearly every benefit this approach offers someone buying a first home, and it is why the strategist now steers so many clients toward it.
Across that decade, the strategist has advised hundreds of buyers who ran into the same barriers: rising interest rates, strict lending standards, and property prices that refused to level off. Given those conditions, the strategist describes buying before a home is completed as one of the strongest options for first-time purchasers. The main alternative is an older, established house, which tends to bring maintenance burdens and hidden repair bills that drain a buyer’s savings. A brand-new home secured before completion delivers both financial and lifestyle advantages.
Start with cost, since affordability is the largest hurdle for entry-level buyers. In the conventional market, established homes often come with inflated price tags driven by Immediate demand, leaving buyers with little room to negotiate. Off-the-plan sales operate differently. Developers frequently price units competitively to attract early buyers and keep a project moving. That allows a buyer to settle on a price today, whatever direction the broader market takes later.
The way payment works also breaks from an ordinary purchase. Buyers are not asked to hand over the full sum, or a large lump payment, up front. The usual arrangement requires a modest deposit, often around 10%, with the remaining balance due only once construction is complete. That interval acts like a runway. For months, sometimes years, buyers can keep saving, sharpen their budgets, and build up their finances without mortgage repayments weighing on them. For many young professionals and families, this breathing room moves homeownership out of the realm of distant hope and into the realm of a realistic goal.
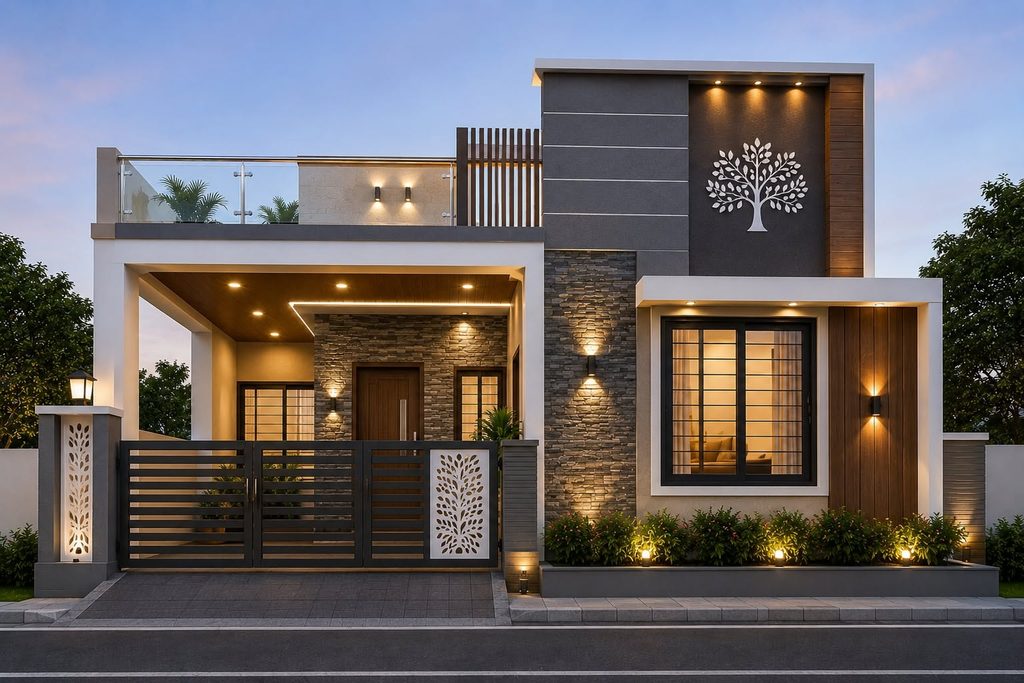
Government support forms a second layer. Financial assistance programs exist to help first-time buyers get past the standard obstacles, and while the rules change often, the key supports remain in place. Among the most significant is the government-backed First Home Loan initiative. Banks typically want a 20% deposit, a figure that can take years, even a decade, of disciplined saving to accumulate. Low-deposit schemes slash that requirement, in some cases down to 5%.
Pair such a scheme with an off-the-plan purchase and the advantage compounds. The buyer lays claim to a future home at today’s agreed valuation while contributing only a small share of the cost at the start. The time needed to reach the first rung of the property ladder shortens considerably. The buyer is also insulated from two stubborn pressures: ever-higher rents and steadily climbing property prices.
Uncertainty runs through every property cycle. Market corrections, interest rate shifts, and sluggish economic conditions make many buyers hesitant to commit their money. Yet that is precisely the environment in which an off-the-plan purchase proves its resilience. The price is settled on day one, while the market keeps moving throughout the construction period.
If values climb in that window, the buyer may already hold added equity before the keys change hands. If the market stalls for a while, the contract price stays put, so the buyer avoids paying a peak-level figure. This built-in cushion protects the investment. A traditional purchase that settles Immediately cannot match that long-term financial security.
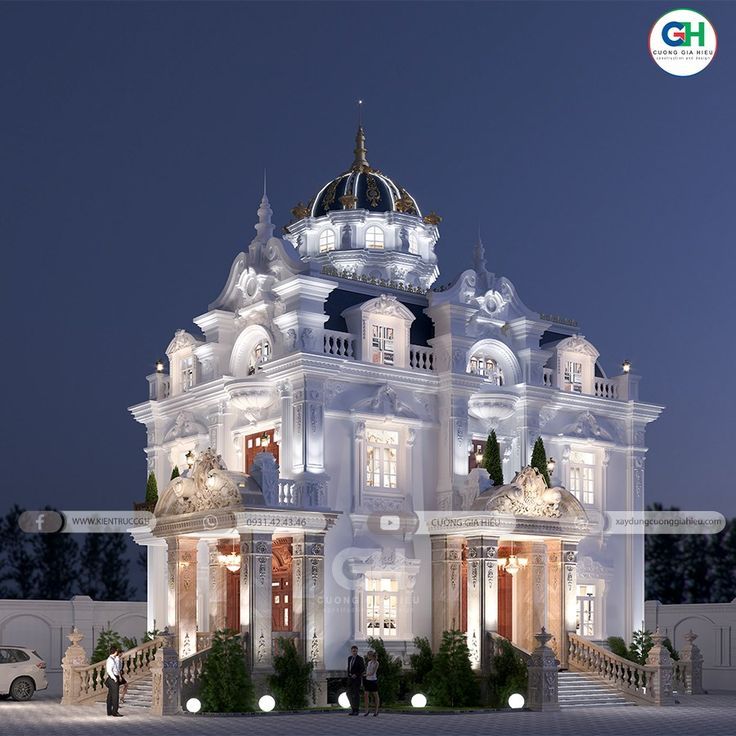
Money is only one dimension, because a home is also a personal choice. Buyers today expect more from where they live than previous generations did. They want energy efficiency, smart-home technology, clean minimalist design, and easy upkeep. Developers of modern off-the-plan projects understand those preferences well. New developments therefore feature contemporary architectural design, double-glazing, high-grade insulation, solar power provisions, and sustainable building materials. These features Improve daily life, and they also reduce running costs for utilities and maintenance.
By contrast, an aging established home often requires costly renovations soon after purchase, along with unexpected plumbing failures and expensive structural upgrades. An off-the-plan home meets the latest building codes and carries comprehensive developer warranties. It should also remain appealing to future buyers or tenants if the owner’s circumstances change.
Entering the property market for the first time feels intimidating, but the strategist argues that the right approach changes the outlook. Careful financial planning, low-deposit lending, protection against market swings, and efficient modern design together form a clear, structured route to long-term wealth and a stable home. For those ready to leave renting behind and see how an off-the-plan purchase could speed up their path to ownership, the strategist’s property advisory team offers personalized strategy consultations.
To sum up, a fixed price, a small upfront deposit, extra time to save, and a home built to current standards are what make off-the-plan buying such a practical option for first home buyers. The road to a first home may be shorter than many people assume. And for anyone still weighing renting against buying, the question worth asking is how much of that road a locked-in price and a long settlement window could cover.
If this breakdown gave you something useful, tap the subscribe button so the next one finds its way to you. A quick like helps other viewers discover the video, and switching on the notification bell means you will hear about new stories the moment they go live.”