Picture two households on the same street in the same neighborhood.
One writes a rent check to a landlord every month, and the other pays down a mortgage. Give it a number of years, and the difference between their financial positions makes the entire case for one path over the other. Real estate professionals hear some version of this scenario constantly, and it is the picture an industry author uses to open his analysis.
That author has spent ten years in property markets. He has steered hundreds of clients through purchases and observed several economic cycles up close. His conclusion is that renting provides short-term flexibility, while owning real estate remains the foundation of lasting wealth. Seasoned investors, he says, do not stop at what a home costs each month. They ask where their net worth is headed. By that measure, he argues, buying an apartment is the stronger long-term choice for both finances and quality of life. Buyers in well-connected suburban areas, including the residential corridors of Tripunithura, are increasingly reaching the same view.
His first point concerns the pressure tenants live under. Inflation keeps climbing, and landlords commonly raise the price each time a lease comes up for renewal. A renter then has two options: accept a steep increase, or take on the draining and costly work of relocating. People renting nearby can face annual hikes of 5 to 10%. A fixed-rate home loan removes that risk. The monthly housing payment is set in advance and entirely predictable, so the baseline cost holds steady. Once the loan is fully repaid, the owner lives rent-free for life, which frees up a large share of cash flow for retirement or other investments.
Renting has a deeper flaw too. Every dollar that goes to a landlord is gone for good, an expense that returns nothing. A mortgage runs in the opposite direction and works like a savings plan you cannot skip. Each installment reduces the loan principal and increases your equity in the property. Over 10 to 15 years, that gradual shift from tenant to owner reshapes your balance sheet. Real estate has also historically protected owners against inflation. Prices for goods and rental rates rise year after year, but property appreciation lifts the value of what you hold. Your wealth compounds, and your financial footing becomes firmer.
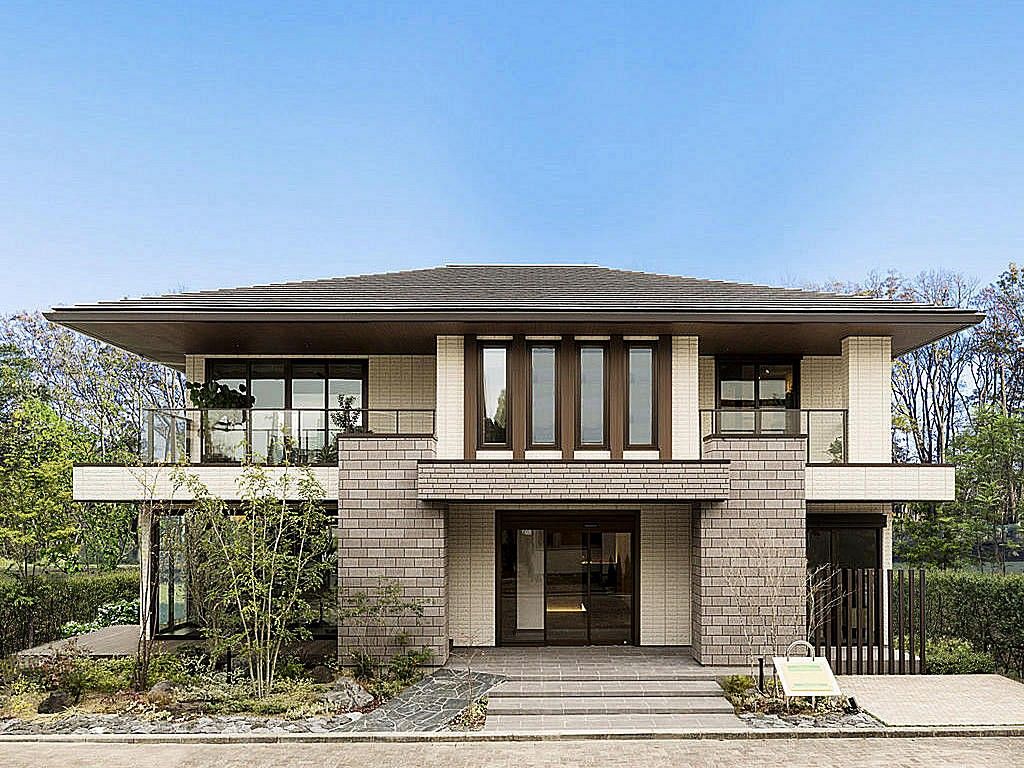
Control over the living space marks another dividing line. Landlords seldom welcome tenants who want to knock down walls, lay custom hardwood flooring, or remodel the kitchen. A renter lives within limits that someone else drew. An owner has complete creative freedom. You could paint the living room in deep earth tones, install high-end smart-home systems, or redesign the whole kitchen layout without asking anyone for approval. Putting money into a premium apartment lets you shape a home around your own taste, and that Improves daily life.
Taxes tip the balance further toward buyers. The government incentives attached to buying property are ones renters can never claim. Tax codes strongly favor homeowners by allowing deductions on both the interest and the principal repayments of a home loan. Those deductions lower your taxable income every year, acting as a quiet subsidy on the purchase. First-time buyers can also tap various government schemes and structural incentives, which make entering the market more rewarding still.
An apartment can earn money as well. Real estate is versatile because it can pay you as well as house you. Buy a spacious 2 BHK or 3 BHK unit, and you keep the option of generating passive income from it. In high-demand residential areas like Tripunithura, rental yields remain exceptionally strong. You might lease out a spare room. You might rent out the entire apartment while you are away on a career relocation. Either way, the property becomes a second source of revenue, one that can comfortably cover its own upkeep or feed an investment portfolio.
Credit health is another gain, and it comes from the discipline a mortgage demands. That discipline spills over into the rest of your financial life. Regular, on-time EMI payments register as positive marks with credit bureaus, and over time they build a strong credit history. A high credit score widens your borrowing options later, whether you want to fund a business, buy a second property, or lock in favorable rates on other loans. Owning a home instills habits that keep paying off for decades.
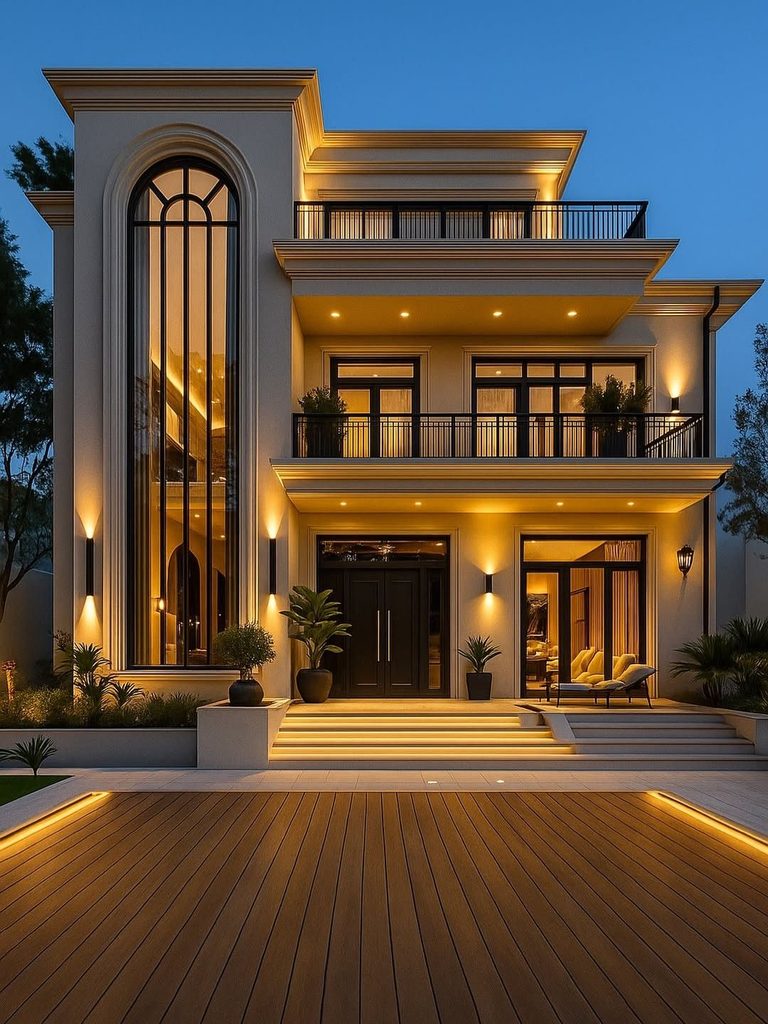
Not every benefit shows up on a spreadsheet. Homeownership also brings lifestyle gains that are harder to quantify. Bouncing from one rental to the next wears people down emotionally, and families with children feel it most, since children need stable school districts and friendly neighborhoods. Buying a unit in a modern gated community or a luxury apartment complex opens the door to better shared amenities. Those include landscaped parks, state-of-the-art fitness centers, swimming pools, and multi-tier security around the clock. A complex built by a leading builder and run by professionals is likely to deliver well-kept infrastructure, reliable maintenance, and a calm atmosphere. Standalone rental houses rarely match that.
The author finishes by answering four questions that readers commonly ask. Why is buying better than renting? Buying builds equity over the long term, protects you from unpredictable rent increases, and gives you complete freedom over your space, while renting returns nothing financially. What is the biggest advantage of buying over renting? Equity. Your monthly payments go toward a tangible asset that gains value over time, rather than toward paying off someone else’s mortgage. How do apartments compare with independent houses on lifestyle? Apartments offer integrated community living, top-tier security, shared recreational amenities, and much lighter maintenance duties for each owner. Is real estate a good hedge against inflation? Yes. Property values and rental equivalents tend to rise along with inflation, which protects your purchasing power and lets the asset outperform ordinary cash savings.
His bottom line is that moving from tenant to owner is a milestone that reshapes your financial path. Buying an apartment brings together wealth accumulation, fixed housing costs, a stable lifestyle, and long-term security in a way renting cannot. For anyone browsing apartments for sale in Tripunithura, he says, a purchase there means stepping into a growth-oriented market, and he calls it a smart move toward lasting financial freedom.
The piece ends with a pitch from Siddhi Homes, which says it takes pride in building premium living spaces designed for comfort, complete security, and strong future appreciation. The company invites readers to explore its latest residential projects and take a confident first step toward a home that is truly their own.
Reduced to its core, the argument rests on a single contrast. A rent payment disappears, while a mortgage payment builds equity, steadies housing costs, and strengthens credit over time. Which of those two paths your monthly money follows is the real decision behind buying versus renting.
If this breakdown helped you think through the decision, subscribe to the channel so you never miss a new report. Hit the like button to help more viewers find this video, and turn on the notification bell so the latest stories reach you the moment they go up.”