Global Housing Market Outlook: Navigating 2026 Trends, Construction Shifts, and Regional Demographics
The global real estate landscape is undergoing a structural transformation as it responds to macroeconomic shifts, demographic pressures, and evolving environmental regulations. With worldwide demand for new residential properties reaching 53.0 million units and projected to expand at a compound annual growth rate of 2.7% through 2030, real estate developers, investors, and policymakers face both unique opportunities and complex hurdles. As an industry analyst with over a decade of experience tracking global residential development, I see this period as a critical crossroads. The market is moving away from traditional, resource-intensive construction toward high-efficiency, climate-resilient models designed to bridge chronic housing shortages.
Understanding these dynamics requires looking beyond national borders to examine how regional variations in housing stock, construction techniques, and government policies are shaping the future of global housing.
Shifting Ground: Regional Dynamics in New Housing Construction
New housing construction is shaped by a complex interplay of demographic pressures, economic conditions, and evolving policy environments across distinct global regions.
In North America, developers are heavily leaning into lower-density, single-family residential construction. Aging millennial demographics entering their peak homebuying years—combined with improving household income conditions—are fueling incremental growth in suburban and exurban markets, particularly across lower-cost Sun Belt regions where land availability is more favorable. In contrast, urban multifamily markets face compressed profit margins, higher vacancy rates, tighter commercial real estate credit, and mounting construction costs, making single-family builds far more attractive for near-term capital deployment.
Meanwhile, Central and South America are propelled by middle-class expansion and steady internal migration. New residential projects in these nations increasingly focus on climate resilience and affordability, addressing long-standing infrastructure deficits. Western Europe is aggressively turning toward energy-efficient building standards, sustainable materials, and modular solutions to modernize its aging housing stock. Eastern Europe faces significant headwinds from persistent inflation, localized labor shortages, and subdued consumer confidence, limiting rapid expansion.
In the Asia/Pacific region, rapid urbanization and aggressive government-backed housing initiatives continue to spur development. However, China stands out as a critical cautionary tale, where chronic oversupply in smaller cities and financial instability within the real estate sector have weighed heavily on new construction starts. Across Africa and the Middle East, surging population growth and urban expansion are driving robust demand, with large-scale affordable housing initiatives taking root to accommodate swelling city populations.
Aging Homes and the Widening Quality Gap
An examination of existing housing stock across global regions reveals critical disparities in quality, formality, and readiness for future environmental and technological challenges.
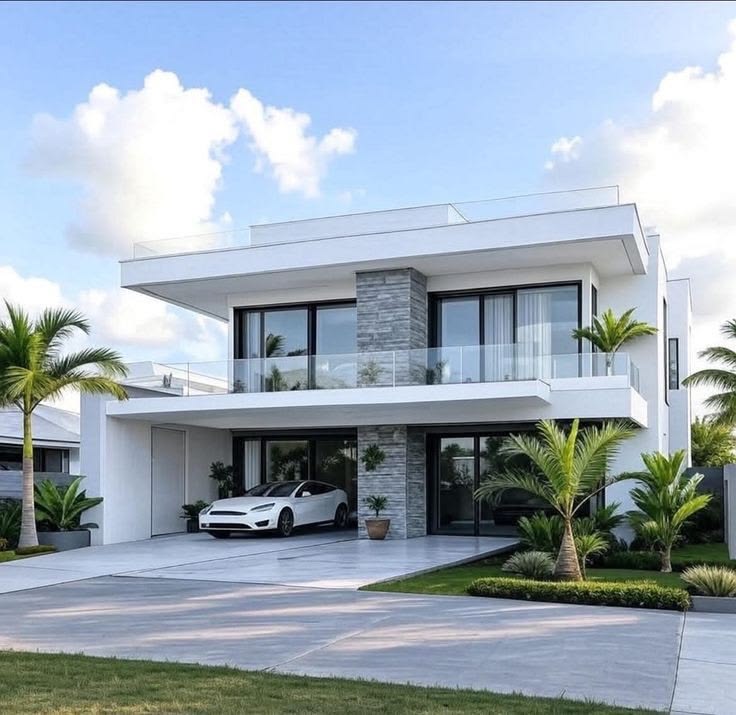
In North America and Western Europe, older housing stock built prior to 1980 dominates the market, driving massive consumer demand for comprehensive energy retrofits, smart home technology integrations, and modern architectural redesigns. Detached single-family homes still prevail across North American suburbs, whereas high-density rental housing characterizes much of Western Europe’s urban centers.
In contrast, Central and South America’s housing stock—much of it informal or self-built—struggles with severe infrastructure deficits and climate vulnerability. These exact issues are mirrored in parts of Africa and the Middle East, where substandard dwellings remain widespread. Eastern Europe’s legacy of Soviet-era concrete blocks presents major renovation needs, further complicated by fragmented ownership models and demographic decline.
In the Asia/Pacific sphere, the contrast is remarkably sharp: gleaming modern residential towers in advanced economies stand directly beside informal settlements in emerging nations, prompting governments to step in with targeted housing programs aimed at formalizing and upgrading existing stock.
Climate Resilience, Modular Construction, and Government Policy
Governments worldwide are responding to acute housing deficits with targeted incentives, financial subsidies, and public-private partnerships designed to expand access to shelter. At the same time, mounting climate concerns are fundamentally reshaping how and where residential properties are built—ranging from flood-resilient engineering in South America to extreme heat-ready architectural designs in the Middle East.
To combat persistent skilled labor shortages and manage ballooning project timelines and material costs, the industry is widely adopting modular and off-site construction methods. Particularly prominent in Europe and advanced Asian markets, prefabrication allows developers to accelerate delivery schedules while minimizing on-site waste.
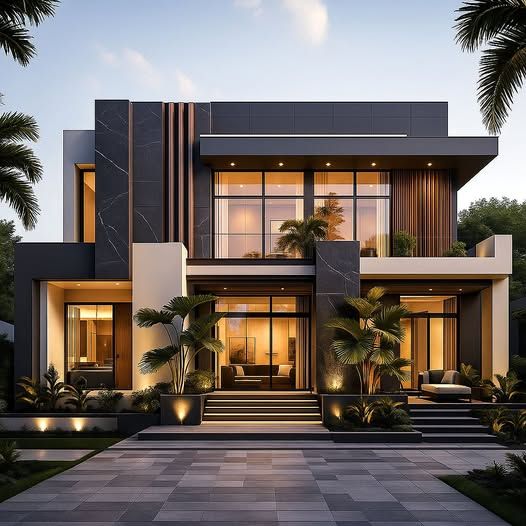
Demographic shifts—ranging from aging populations in Japan and Eastern Europe to young, fast-growing cities across Africa—are also directly influencing housing design, accessibility features, and tenure preferences. Even as global housing markets diverge in pace and structure, they share a universal imperative: the urgent need for resilient, energy-efficient, and inclusive housing stock capable of accommodating shifting social and environmental realities.
Comprehensive Market Scope and Segmentation
Analyzing the broader macroeconomic outlook requires a standardized framework. Comprehensive market reports examine residential construction through both total housing stock and annual new housing unit production across key geographic territories:
North America (United States, Canada, and regional markets)
Central and South America
Western Europe
Eastern Europe
Asia/Pacific
Africa and the Middle East
Data segmentation encompasses private developments (both owner-occupied and rental), public or social housing initiatives, and informal settlements. Housing units are further categorized by structural type into single-family detached homes and multifamily properties—including apartments, condominiums, and townhouses—with all physical volume metrics evaluated in both total units and square meters of residential floor space.
Looking Ahead: Strategic Next Steps for Industry Stakeholders
Navigating the complexities of the current residential construction cycle requires precise market intelligence, robust financial modeling, and a clear understanding of regional regulatory shifts. Whether you are evaluating commercial real estate investments, assessing supply chain vulnerabilities in off-site manufacturing, or planning large-scale residential developments, having access to granular data is essential for long-term profitability.
<FollowUp label=”Want me to break down the specific regional housing forecasts and valuation metrics for 2030?” query=”Break down the specific regional housing forecasts, construction expenditure data, and valuation metrics for the global housing market through 2030.”/>