A professional who spent ten years working with residential buyers and developers, through market cycles that swung hard in both directions, keeps returning to one conclusion: for would-be homeowners, waiting carries a price.
Property values rise, savings build more slowly, and the distance between the two can start to look Impossible to cross. One option, this professional observed, keeps pulling aspiring owners back. It is buying a home before construction is finished, and the argument for it is that an early purchase puts time on the buyer’s side.
Current conditions strengthen that argument. Lenders enforce strict rules, building costs keep climbing, and housing supply remains tight. In that environment, buying off-the-plan has become a calculated strategy rather than a gamble. Many savvy buyers now pass over older existing homes, and the crowds of rival bidders that come with them, and choose new builds that can anchor their finances. The reasons this route suits first-timers in a complicated market follow.
The deposit is where many buyers stall. Assembling the traditional twenty percent is often the hardest stretch of the whole journey. Government help and specialized banking products continue to evolve in support of new construction. Some grants come and go as economic policy shifts, but programs like the First Home Loan scheme remain vital lifelines. These government-backed programs can reduce the deposit to as little as five percent for eligible buyers who purchase new builds or off-the-plan property.
Pairing a low-deposit scheme with an off-the-plan purchase also shortens the road to ownership. Consider a person who saves diligently for five to seven years while property values outrun every dollar set aside. A buyer who commits early and secures the asset avoids that trap, because time carries part of the load. Lenders add to the benefit, since they often view financing for new builds more favorably. Modern dwellings built to current codes present a lower Immediate risk profile.
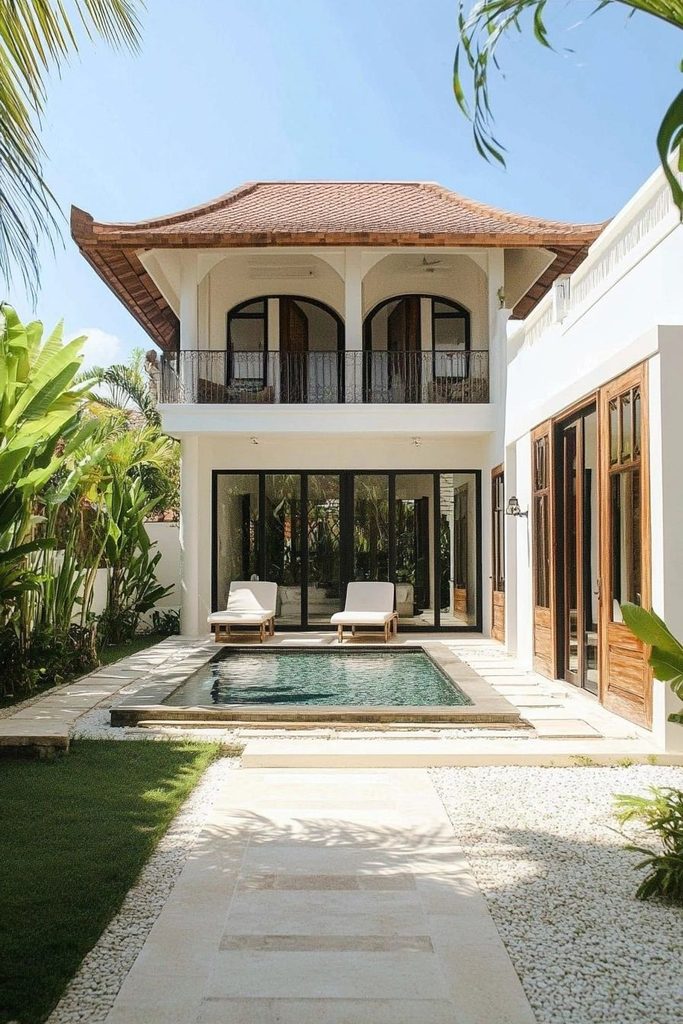
The structure of the deal explains much of the appeal. Affordability may be the biggest barrier facing everyday buyers. Established homes in prime suburban pockets often command sky-high prices, and tight borrowing limits or heavy upfront capital requirements keep many people out of reach. Buying something not yet built works differently from buying something already standing. The buyer usually locks in the price with a fairly modest deposit, often ten percent, and owes the remaining balance only once construction wraps up.
That arrangement delivers three practical advantages. The first is a fixed price. Because the buyer sets today’s figure, any significant rise in values during construction produces capital gains before the buyer has even moved in. The second is a longer savings window. Settlement can arrive months or even years later, which gives the buyer extra runway to keep saving and softens the burden of a mortgage. The third is lower maintenance cost. A brand-new building spares its owner the Immediate repair bills, roof replacements, and plumbing overhauls that so often weigh on older properties. As an investment, the purchase lets the buyer enter the market with a smaller initial footprint and spread the financial exposure over a manageable timeline.
Market cycles bring their own anxiety. Property markets rise and fall, and slow periods or interest rate adjustments can make buyers hesitate, worried they will purchase at the peak. An off-the-plan purchase works as a natural hedge against short-term volatility. Construction typically takes twelve to twenty-four months, and by the time the keys change hands, swings during the building phase have often smoothed out. If the wider market grows steadily across that stretch, the buyer’s equity position strengthens before settlement.
Location is another factor. Modern developments are rarely standalone structures. They are master-planned communities, designed around future infrastructure, transport links, and commercial hubs. A future-proofed off-the-plan property places its owner in the direction urban growth is heading. That supports stronger long-term capital appreciation than stagnant, land-locked older neighborhoods can offer.
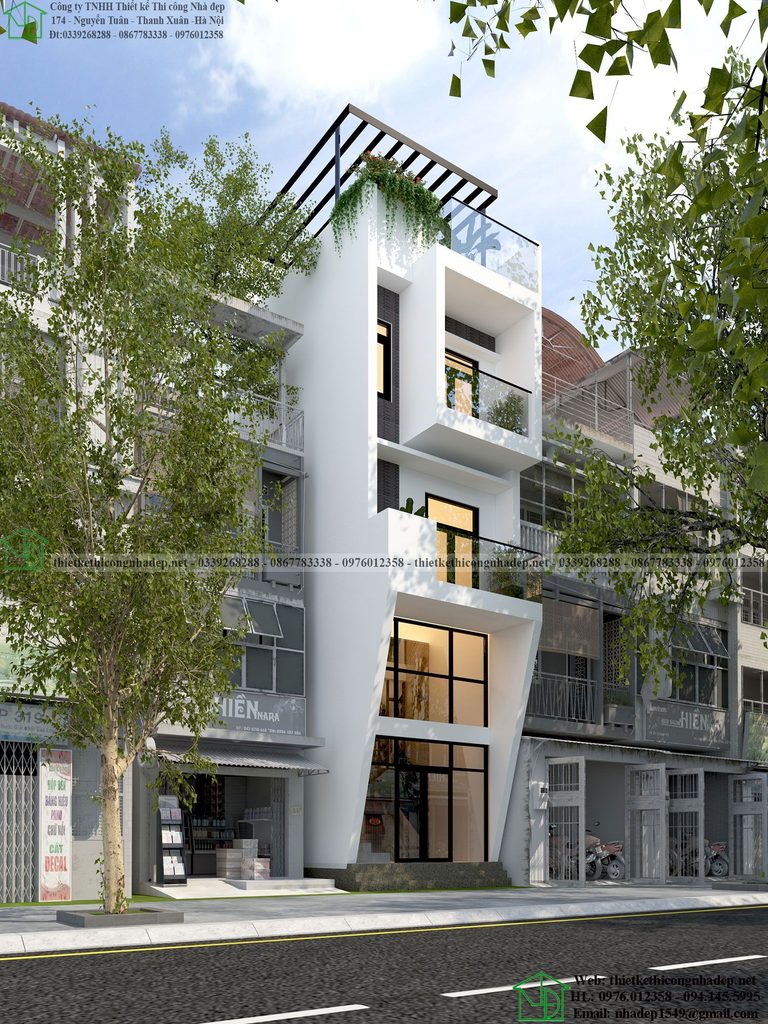
Living standards complete the picture. Today’s homeowners ask more of their living spaces than earlier generations did. Energy efficiency, smart home technology, open-plan layouts, and acoustic insulation have shifted from luxuries to expectations. Older homes frequently need costly retrofitting before they reach contemporary energy standards. An off-the-plan home is guaranteed to comply with the latest building codes, insulation standards, and environmental ratings. Developers increasingly include sustainable features such as double glazing, high-performance heat pumps, solar panel readiness, and water-efficient fixtures.
Those inclusions bring lower ongoing utility bills and a healthier living environment. They also match the consumer preferences that will drive market demand for decades. The outcome is an asset that remains highly liquid and attractive if the owner eventually sells or rents it out.
Taken together, these points show that entering the property market does not have to feel overwhelming. Once first-time buyers understand the strategic benefits of off-the-plan property, they can sidestep many traditional barriers, from excessive deposit requirements to costly upkeep on aging homes. Low-deposit financing, price-locking mechanisms, and modern, energy-efficient designs combine into a clear roadmap to homeownership through a purchase made before construction ends. For those ready to quit renting and take charge of their financial destiny, exploring off-the-plan opportunities could be the most Important decision of the year. The expert advisory team is available to review current developments, discuss financing eligibility, and help identify a property that fits long-term goals.
Four points hold the case together: a smaller deposit, a locked-in price, a longer savings runway, and a home built to today’s standards. What remains for each first-time buyer to weigh is how far those advantages could reshape the road to a front door of their own.
If this breakdown gave you something useful, hit the subscribe button so the next video lands right in your feed. Give it a like to let us know the time was well spent, and switch on the notification bell so the latest news reaches you the moment it goes live.”