A signed deed and a set of keys mark the finish line of what is, for most people, one of the biggest financial and emotional commitments they will ever make.
An agent who has spent ten years working directly with buyers, negotiating competitive mortgage refinancing deals, and studying real estate trends says the pattern never changes. The process feels daunting at the outset, yet it turns orderly once it is broken into deliberate phases. What follows is an expert-level roadmap that carries a hopeful dreamer through the U.S. housing market and into ownership.
The work starts before any listing is opened or any open house is attended, with a rigorous look at your own finances. Across ten years of advising clients, many buyers have fallen for homes that sat beyond their true means. The safeguard is basic arithmetic. Total your gross income, your recurring monthly debts, and your everyday living expenses, then use those figures to calculate your debt-to-income ratio, or DTI. Lenders scrutinize that number. A realistic budget fixed at the start steers you toward homes with manageable monthly mortgage payments and protects your long-term financial stability.
The down payment is the second stage, and it remains a cornerstone of home ownership. On traditional conventional loans, a 20% down payment is often viewed favorably because it removes the need for private mortgage insurance, known as PMI. Still, several programs allow qualified buyers to put down far less, sometimes only 3% to 5%. A savings account is not the only source. First-time home buyer assistance programs, down payment grants, and employer-sponsored housing benefits can each shorten the climb.
Third comes research into local conditions. Real estate is hyper-local, but a view of the broader housing market is essential for informed, profitable decisions. Study individual neighborhoods, track property price trends both historical and current, and look into municipal or commercial developments on the horizon that could affect future appreciation. Understanding inventory levels and the local balance of supply and demand also strengthens your hand in negotiations once you are ready to act.
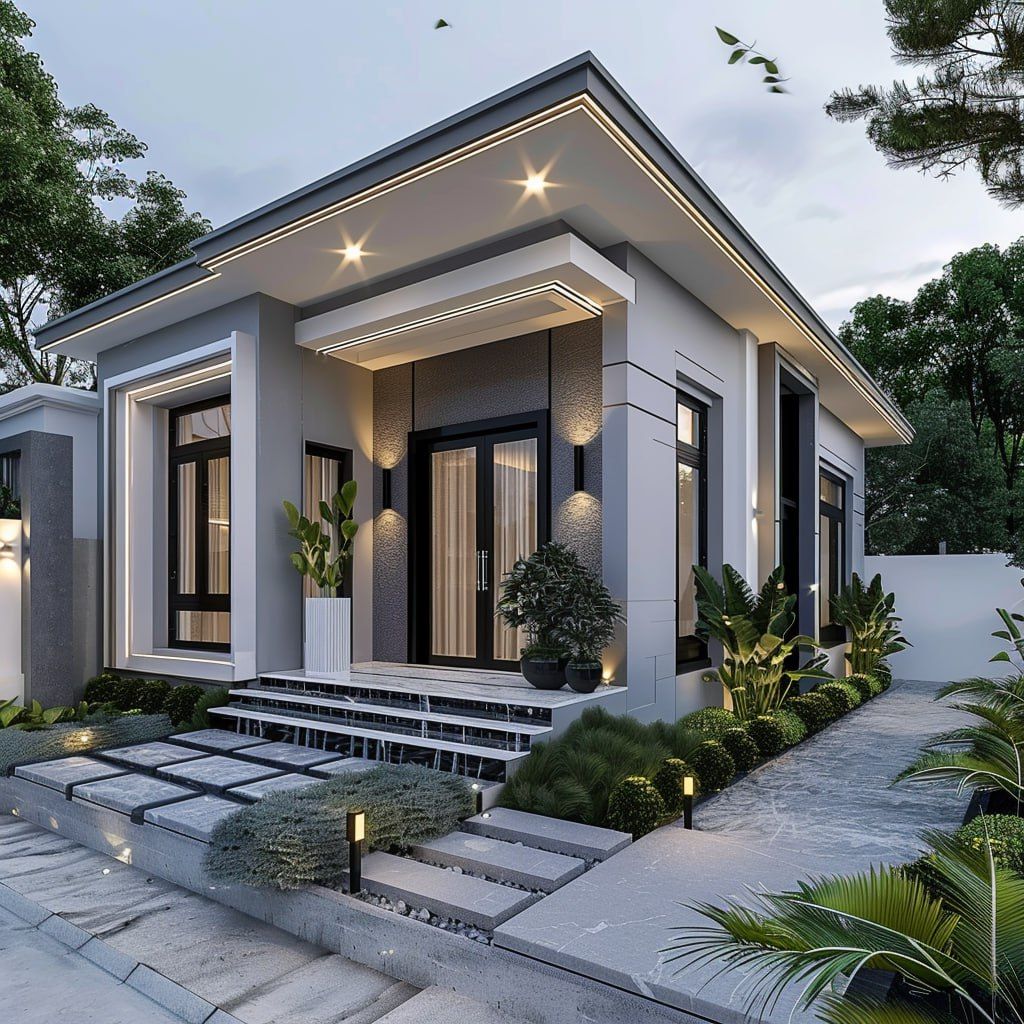
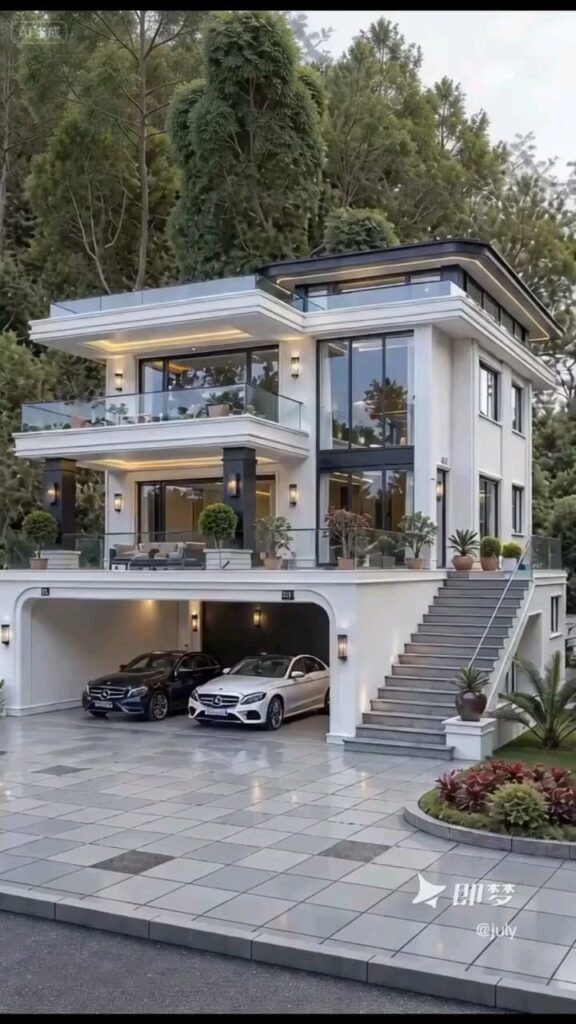
Eighth is due diligence, your main shield against unforeseen financial liabilities. Hire a licensed home inspector to evaluate the structural integrity, roof condition, plumbing, electrical systems, and HVAC units. Read through the title search report, the HOA covenants if applicable, and the environmental disclosures. Any problems uncovered during this contingency period give you leverage to negotiate repair credits or price reductions before you move forward.
In the ninth stage, the due diligence contingencies have been cleared, and your lender advances the loan file from conditional approval to final underwriting. Provide requested documents promptly, such as updated bank statements or employment verifications, so the closing timeline holds. Lock in your interest rate if you have not already, read your Closing Disclosure, or CD, carefully, and confirm the final cash-to-close figures.
The tenth and final stage is closing day. You sign the final loan documents and legal paperwork, wire your closing funds, and complete the official transfer of ownership. Once the deed is recorded at the county office, the keys to your new property are yours. Becoming a homeowner is a remarkable achievement, and it deserves a moment of celebration as you step through the door.
Each stage rests on the one before it, from an honest accounting of your finances to the recording of the deed and the handing over of the keys. That sequence is what makes a daunting purchase manageable.
If this roadmap was useful to you, subscribe to the channel and hit the like button on the video. Turn on the notification bell as well, so the latest news reaches you the moment it is published.”