Real estate rewards the investor who is still standing after the cycle turns.
Over ten years of working in the American housing market, one pattern has stood out: some portfolios ride out downturns and keep growing, while others collapse under them. The difference rarely comes down to luck. Property investing is a marathon, not a sprint, and it calls for discipline, foresight, and a sturdy framework. That holds whether you are buying your first single-family rental or expanding a commercial portfolio across several markets. A clear long-term strategy works as the master blueprint, and it should be built for today’s economic conditions.
Start with purpose. Without defined goals, an investor can easily be pulled into poor deals by short-term market hype. The core questions are simple. Do you want steady passive income, a growing stake of home equity, or hard assets to leave to the next generation? Your timeline then shapes the method. Fix-and-flip projects depend on well-timed market moves and aggressive rehabilitation. Long-term buy-and-hold approaches draw their strength from compound growth, amortization, and gradually rising rents. Concrete milestones keep the plan on track, such as a net passive cash flow of three thousand dollars per month within a five-year horizon.
Your own finances come next, and they need a rigorous audit before you look at a single property or neighborhood comp. Lasting wealth rests on balance sheet mastery, creditworthiness, and smart leveraging. On capital reserves and budgeting, the down payment is only part of the picture. Closing costs, insurance premiums, property taxes, and cash reserves for vacancy periods all belong in the budget, along with capital expenditures such as roof replacements or HVAC upgrades. On credit, lenders reward fiscal discipline, and a score of 740 or higher unlocks the lowest mortgage interest rates, which cuts your long-term borrowing costs significantly. On advisory partnerships, bring in a certified financial planner early, along with a specialized CPA who knows real estate tax codes, depreciation schedules, and entity structuring through LLCs.
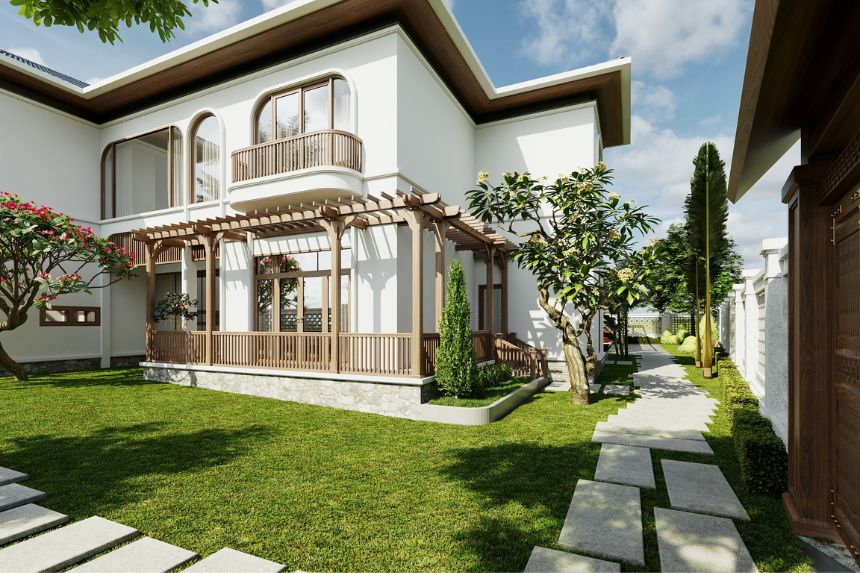
Location is the heart of property performance. Successful investors are not simply buying buildings. They are buying into local economic ecosystems, and studying both macroeconomic indicators and micro-neighborhood trends separates a lucrative asset from a financial anchor. Look at employment growth, migration patterns, and local infrastructure developments. Areas where corporate headquarters are arriving or tech hubs are expanding tend to show strong rental demand and upward pressure on property values. Weigh those signals against supply constraints. Where zoning laws or geographical boundaries limit new construction, existing inventory appreciates faster.
Diversification protects that wealth from several directions. Putting all your capital into one property type or one neighborhood leaves you exposed to local downturns. For asset class mix, pair residential single-family homes or multi-family apartment complexes with commercial real estate or light industrial space, so you capture different yield profiles. For geographical spread, look beyond your own backyard. Holdings in different states or metropolitan statistical areas shield your overall returns if one local industry falters. For strategy blending, combine cash-flowing rentals with capital-growth projects, which balances liquidity needs against long-term wealth accumulation.
Operations determine your net operating income. As the portfolio grows, the choice between self-management and a professional property management company becomes a critical one. Managing properties yourself removes third-party fees but eats up a great deal of time. Professional managers usually charge a percentage of monthly gross rents, and in return they handle tenant screening, lease enforcement, emergency repairs, and legal compliance. Either way, set up proactive maintenance protocols. Reserving one to two percent of a property’s value each year for routine maintenance keeps minor wear and tear from turning into costly emergency repairs.
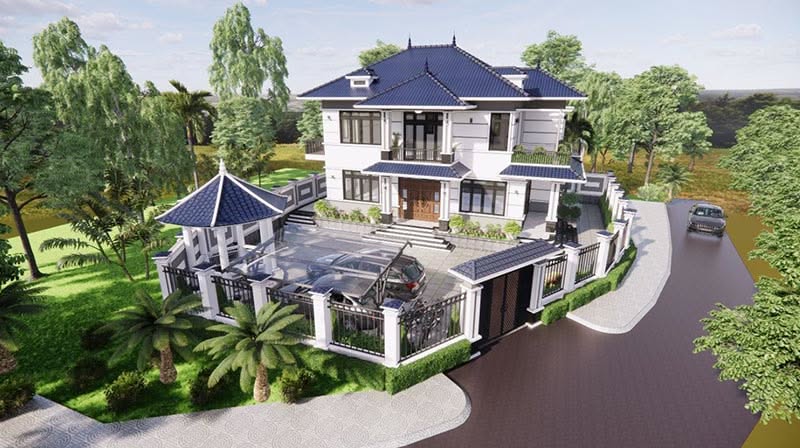
An entry plan without an exit strategy is an incomplete investment thesis. Knowing how and when you will sell or transition your assets is essential to maximizing cumulative returns. With strategic selling and 1031 exchanges, you can sell appreciated properties at peak market cycles, then use a 1031 exchange to defer capital gains taxes and roll equity into larger, higher-performing assets. With asset refinancing, you can tap accumulated equity through cash-out refinances when interest rates are favorable, freeing capital for later acquisitions without triggering taxable events. With estate and succession planning, an estate attorney can help structure trusts or transfer ownership smoothly to heirs, which minimizes probate delays and estate tax liabilities.
Put together, the pieces form one framework: clear goals, a protected balance sheet, intelligent diversification, and a plan for every stage of an asset’s life. Long-term success in the property market goes to those who pair patience with rigorous analysis and adaptability, and that combination positions an investor for enduring financial independence.
If this breakdown gave you something useful to build on, hit the subscribe button so the next video lands in your feed. Give the video a like to help other investors find it, and turn on the notification bell so you never miss the latest updates. Your next step in building lasting wealth could be one click away.”