Over more than ten years of advising residential buyers, one real estate adviser has watched hundreds of families wrestle with the same decision: keep renting, or step into homeownership.
The choice blends hard economics with a personal need for stability. After a decade of market cycles, inflation spikes, and shifting neighborhoods, the adviser says both the numbers and the psychology point the same way. Buying a residential property, especially in high-demand urban corridors, reshapes a household’s long-term wealth trajectory.
Most discussions today begin and end with monthly cash flow. Seasoned investors and financial advisors say that comparing short-term rent against a mortgage payment misses the bigger picture. The case for buying rests on security, wealth accumulation, and peace of mind, none of which leasing can match.
Start with equity. The biggest weakness of renting is that the money is gone for good. Each dollar paid to a landlord produces no return. A purchase turns the same monthly housing cost into an enforced savings plan. Part of every mortgage installment reduces the principal, and that steadily builds home equity. The apartment works like a piggy bank that also pays dividends. Across a typical 15- to 30-year span, real estate has historically outpaced inflation, so the asset grows in value on its own. A renter finishes a lease with nothing to show for the payments. A homeowner ends up with a financial cushion that can fund retirement, education, or future investments.
Rent increases are the next issue. Anyone who has rented for more than a couple of years knows the anxiety of the annual renewal letter announcing a hike. Rental inflation is a persistent reality, driven by market demand and cost-of-living adjustments. A fixed-rate home loan counters that volatility with predictability. The monthly principal and interest stay locked in, so the payment holds steady year after year while the wider rental market keeps climbing. When the loan term ends, the owner enters a stretch of rent-free living, and in retirement the income is no longer tied to housing costs.
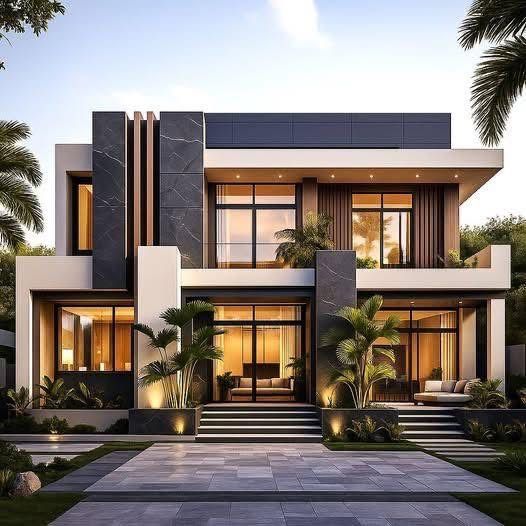
Control over the space matters as well. Renting means living in someone else’s property, and landlords commonly write restrictive clauses into leases. Those clauses can forbid painting walls a bold color, mounting a television securely, or upgrading kitchen fixtures. An owner has full creative freedom. A non-structural wall can come down to open up the kitchen. Custom hardwood flooring, smart home automation, and luxury bathroom tiling are all the owner’s call. Ownership also builds a sense of belonging. A person settled in a permanent community can form deep, lasting bonds with neighbors instead of boxing up belongings every couple of years because of a landlord’s decisions.
Taxes tilt the balance further. Governments worldwide recognize the social value of stable housing, and they reward buyers with significant tax advantages that renters never see. Homeowners can claim deductions on home loan interest and principal repayments, which lowers their taxable income. Regional and national incentives for first-time buyers make entry into the market more attainable. Those benefits offset much of the upfront cost of acquisition and weigh the ledger heavily toward buying.
An apartment is also a versatile financial asset, not only a place to live. Buyers of a spacious multi-bedroom unit can create passive income. They might rent an extra bedroom to a working professional, or lease the entire property if a career move takes them to another city. Either way, the property yields reliable cash flow. In thriving, high-demand residential areas, where urban expansion keeps drawing new residents, rental demand stays strong. That resilience lets the property generate monthly revenue long after the purchase.
A home loan also builds discipline. Servicing a mortgage anchors personal finances, because each monthly commitment adds to net worth, and that encourages better budgeting and fiscal responsibility. A consistent record of on-time payments boosts the credit score as well. Strong credit opens the way to favorable borrowing terms later, whether the goal is to expand a real estate portfolio, fund a business, or secure low-interest loans.
Inflation is a further consideration. It quietly erodes the purchasing power of cash held in traditional savings accounts, and real estate is a premier hedge against that macroeconomic pressure. As construction materials, labor, and land grow more expensive, existing property values rise with them. Renters pay more when landlords raise rates to match inflation. Owners watch their asset appreciate and capture market gains that protect their purchasing power.
Finally, there is security and lifestyle. Standalone rental houses often leave residents exposed to security concerns and heavy ongoing maintenance duties. Modern apartment complexes, especially those from reputable builders, reverse that picture. Gated communities with round-the-clock surveillance, professional property management, and controlled access points give families an added layer of safety. Residents also get easy access to amenities that would be costly to maintain alone: fully equipped fitness centers, landscaped parks, swimming pools, and community clubhouses. These shared facilities raise daily quality of life while keeping individual upkeep costs surprisingly low.
Three common questions sum up the argument. Why is buying better than renting? Buying builds long-term equity, shields the owner from rising rents, offers complete creative freedom, and provides a tangible asset that appreciates. Renting produces recurring expenses with no financial return. What is the biggest financial advantage of homeownership? Forced savings and asset appreciation. Each mortgage payment adds ownership equity, so the owner accumulates net worth rather than funding a landlord’s investment portfolio. How do modern apartments Improve daily life? They offer high-end community amenities such as security systems, fitness centers, and green spaces, all professionally managed to minimize maintenance hassles for residents.
In short, the move from tenant to homeowner is among the most empowering milestones a person can reach. Equity, predictable payments, tax benefits, passive income, credit growth, and inflation protection all lead to the same conclusion: owning beats renting. For anyone ready to stop paying off someone else’s mortgage and start building a secure, appreciating asset, the team behind this advice invites you to reach out today. They can show their premium collection of thoughtfully designed living spaces and help you take that first confident step toward homeownership.
If this breakdown was useful, hit the subscribe button so you never miss a new report. Give the video a like if it helped, and switch on the notification bell so the latest stories reach you the moment they go live.”