The difference between a smooth first home purchase and a stressful one often comes down to preparation, and the money at stake can run to tens of thousands of dollars over the life of a loan.
A real estate and mortgage professional with ten years in the industry, who has guided hundreds of individuals and families through this transition, says success does not depend on luck. It depends on a strategic, step-by-step framework that turns an intimidating undertaking into something achievable. That framework applies whether a buyer is pursuing conventional financing, looking into first-time home buyer grants, or comparing mortgage rates online.
The process starts well before any listing is opened or any open house is attended. The first task is a clear look at your complete financial health, and clarity is the most valuable asset a buyer can bring to the table. That means auditing your monthly income, your living expenses, and any outstanding debts. Lenders examine your debt-to-income ratio closely, so knowing those figures early prevents unpleasant surprises later. Working out your own affordability threshold keeps you from stretching beyond what you can handle. Meeting early with a professional mortgage broker or lender to talk through your options gives you a realistic framework for your budget.
Next comes the down payment, which remains one of the biggest obstacles for new buyers. Traditional lenders often prefer twenty percent down, since that amount avoids private mortgage insurance. But various loan programs and government grants let qualified buyers purchase with far less, in some cases as little as three to five percent. Whatever the target, the advice is to start setting money aside aggressively and as early as possible. Automated savings accounts, employer-sponsored programs, and authorized retirement account withdrawals, where available in your region, can all speed up the growth of your deposit and strengthen your purchasing power.
Alongside saving, buyers need a working knowledge of the market. Acquiring property successfully requires deep awareness of whether you are operating in a buyer’s market or a seller’s market. That means tracking neighborhoods, studying historical sales data, and watching local economic developments, including upcoming transit lines, school district upgrades, and commercial zoning changes. Each of these factors bears directly on long-term property appreciation. A solid grasp of local dynamics also gives you Important leverage when the time comes to negotiate the terms of a purchase.
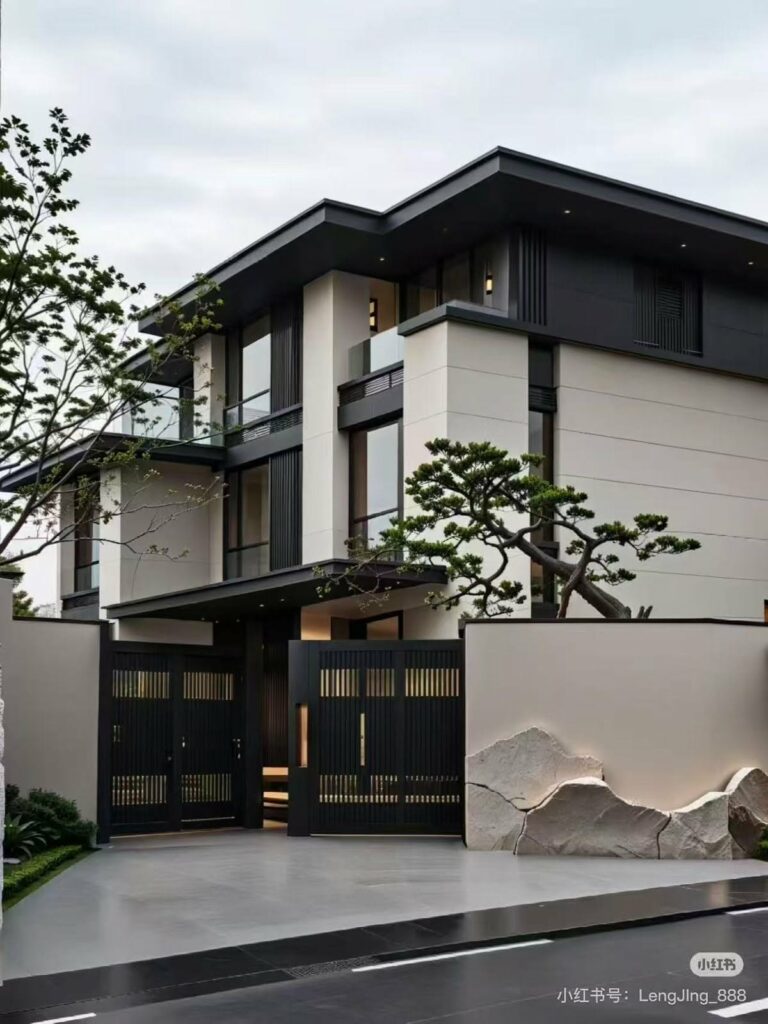
With the groundwork laid, the next step is formal mortgage pre-approval, and the rule here is firm: never shop for a home without a pre-approval letter in hand. The letter shows sellers and real estate agents that you are a serious, qualified buyer who is ready to transact. It also pays to compare offers from multiple financial institutions, credit unions, and digital lenders, looking at interest rates, loan origination fees, and repayment terms. A mortgage product matched to your financial profile can save you tens of thousands of dollars across the lifetime of the loan.
Once your budget and pre-approval are secured, it is time to define what you want in a home. Sit down and divide your non-negotiables from your nice-to-haves. The variables to weigh include geographic location and commute times to major employment hubs, and proximity to quality schools, parks, and retail centers. They also include property type, square footage, and bedroom count, along with structural features such as a private garage, a backyard, or a modern kitchen. A clear checklist keeps your search focused and guards against emotional decisions while you tour homes.
Then the active hunt begins. Buyers can browse digital real estate platforms, arrange private viewings, and attend open houses. An experienced buyer’s agent can provide a major competitive edge, including access to off-market listings and expert local insight. This phase should not be rushed. Touring multiple properties is the best way to understand what value really looks like in your target area.
When the right property turns up, your real estate agent helps you draft a competitive purchase and sale agreement, and this is where your market research pays off. The offer spells out your proposed purchase price, your earnest money deposit, your target closing timeline, and any specific contingencies. Once the seller accepts and signs, the two sides are bound by a contract, and your legal team or closing attorney starts reviewing the documentation.
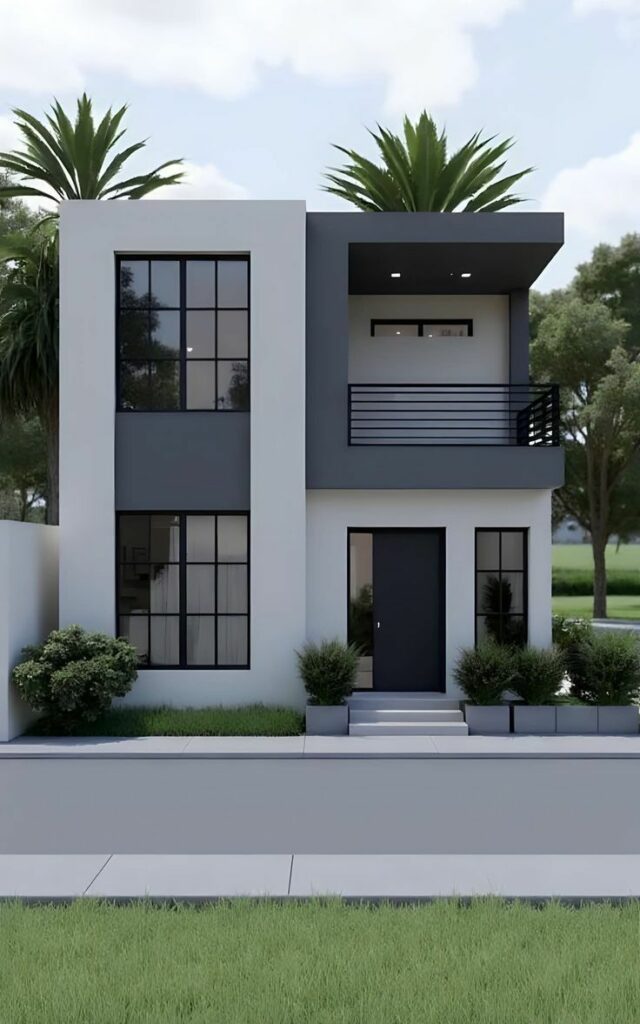
Signing the contract also starts the due diligence period, a step the expert calls non-negotiable for reducing long-term risk. A licensed home inspector should evaluate the property’s structural integrity, roof condition, electrical systems, plumbing, and HVAC units. Buyers should also review title reports, local property disclosures, and municipal records to confirm the land carries no hidden legal disputes, liens, or environmental hazards.
When due diligence wraps up successfully, your lender moves your file from conditional approval into final underwriting. At this stage you confirm the final loan amount, lock in your mortgage interest rate, and go through your Closing Disclosure document carefully. Every fee should match what you expected. Your remaining closing funds must then be wired securely, following the instructions from your escrow or title company.
The last milestone is closing day. You sign the remaining legal transfer documents, pay your closing costs and the balance of your down payment, and see the property title officially recorded in your name. When the transaction is funded and recorded, the keys are handed over. At that point you are a homeowner, ready to move in and begin the next chapter of your life.
Taken together, the path runs from an honest look at your finances, through saving, research, and pre-approval, to inspections, underwriting, and a signature at the closing table. A buyer who follows each stage in order, with a proven roadmap and expert guidance, can turn an overwhelming ordeal into a manageable one.
If this breakdown helped you picture the road to your first home, hit the subscribe button so you can follow along with our future videos. Give the video a like if you found it useful, and turn on the notification bell so the latest updates reach you as soon as they are posted.”