Institutional Investors in Seattle Real Estate: Market Trends, Impact, and Opportunities
The footprint of corporate buyers in metropolitan property sectors frequently ignites fierce public debate. Yet, examining the actual data reveals a nuanced narrative that defies broad generalizations. While national headlines often paint a picture of sweeping corporate dominance, regional realities vary significantly. Analyzing institutional investors Seattle real estate trends shows unique patterns that diverge sharply from national averages, highlighting a landscape defined by localized zoning shifts, distinct buyer demographics, and evolving economic fundamentals.
As an industry expert with a decade of hands-on experience navigating Pacific Northwest property cycles, I have watched how major market shifts affect both individual buyers and portfolio builders. Understanding these mechanics is essential for anyone looking to make informed decisions in today’s complex housing environment.
What Percentage of Seattle Homes Do Institutional Investors Actually Own?
Public perception often overstates the scale of corporate ownership. Nationally, large institutional buyers—typically defined as portfolios holding over 100 single-family properties—own approximately 3% of the total single-family rental stock, according to Brookings Institute research. Even within the top twenty metropolitan statistical areas where these entities concentrate their assets, they account for roughly 12.4% of rental housing. Broader industry analyses, including findings from John Burns Research and Consulting, indicate that large institutional groups purchase less than 2% of all homes nationwide on an annualized basis.
Locally, the numbers remain modest. State legislative testimony indicates that investors accounted for about 9% of all home sales in Seattle. When accounting for smaller, local participants, mid-year transaction data highlights a 16% rise in smaller-scale acquisitions, reinforcing that everyday market participants still form the backbone of investor activity.
Nationally, small-scale participants—those managing fewer than five properties—represent roughly 85% of all investor-owned residential assets. Furthermore, macroeconomic conditions have prompted major corporate landlords to pivot; prominent nationwide housing providers have recorded multiple consecutive quarters of selling more residential assets than they acquire, reflecting a strategic cooling phase across the country.
Why Did Seattle See an Institutional Surge While National Activity Declined?
During periods when broader U.S. transaction volumes contracted under high interest rates, the Pacific Northwest occasionally exhibited counter-cyclical movements. Several region-specific drivers help explain this phenomenon:
Zoning Liberalization and Redevelopment Potential: Legislative updates, such as Washington State’s middle housing measures, require numerous municipalities to permit higher-density residential options on parcels previously restricted to single-family dwellings. Rather than pulling move-in-ready homes off the market, corporate entities often target older properties for structural redevelopment.
High-Income Demographics: The local economy features a large concentration of high-earning professionals who frequently explore real estate as a vehicle for wealth accumulation.
Targeted Transactions: Large-scale portfolio acquisitions, such as the purchase of entire subdivisions or multi-family blocks, can disproportionately skew short-term volume metrics for a single quarter, creating the illusion of a sustained wave rather than a series of isolated transactions.
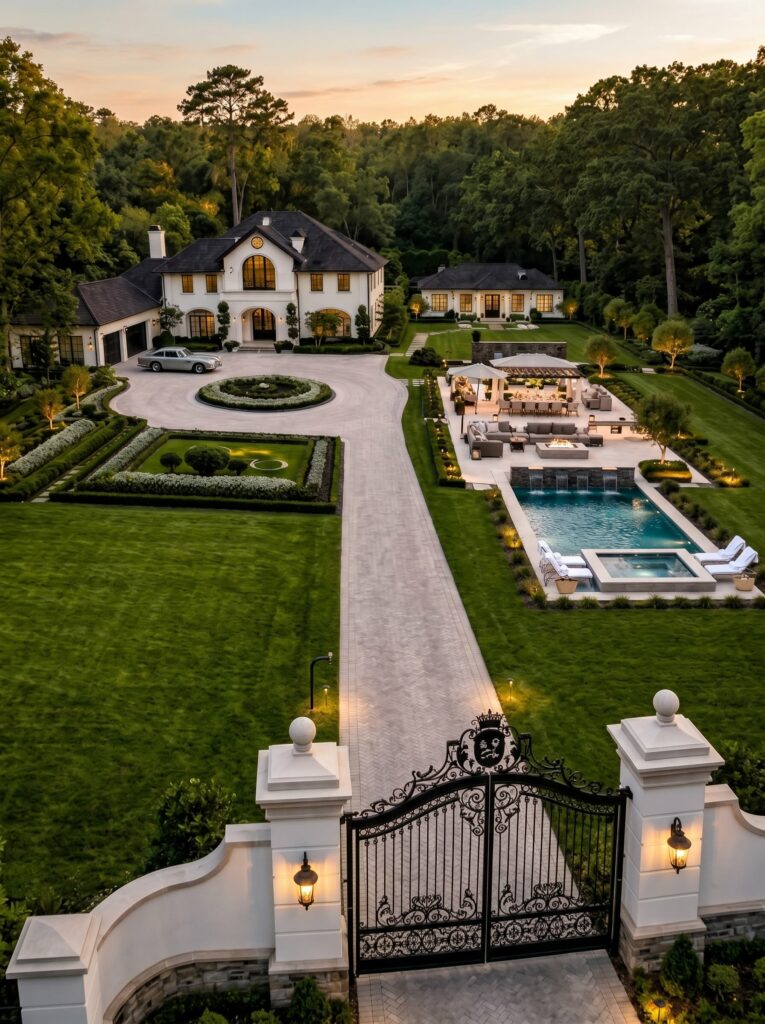
These unique structural elements mean that corporate engagement here serves a different function compared to Sun Belt markets, where buyers often compete directly for traditional starter homes.
How Does Institutional Investor Activity Affect Local Homebuyers?
The friction between corporate entities and retail buyers depends heavily on localized strategy and asset classification. In regions where large buyers focus on teardowns and lot splitting, their presence may stimulate housing density rather than directly depriving first-time buyers of inventory.
A comprehensive review by government accountability researchers examining dozens of post-financial-crisis studies noted that institutional capital did correlate with upward pressure on pricing and lease rates in certain recovering markets. However, measuring their exact long-term influence on homeownership accessibility remains challenging due to shifting definitions and limited longitudinal tracking.
Recent data tracking shows institutional purchases easing, which naturally softens competition for conventional buyers entering the market. Because the local investor share remains low compared to southern or eastern hubs like Miami or San Diego, regional buyers face far less corporate bidding pressure on standard residential purchases.
The Vital Role of “Mom-and-Pop” Real Estate Investors
While institutional brands capture media attention, independent operators dominate the landscape. Nationally, individual landlords owning fewer than five units control the vast majority of investor-owned residential properties.
On the ground in the Pacific Northwest, high-income earners and tech professionals frequently utilize real estate as a long-term wealth strategy. These independent operators exhibit distinct traits compared to corporate boards:
They demonstrate greater flexibility on negotiation timelines.
They often maintain direct oversight of asset upkeep rather than relying on multi-layered corporate management structures.
They frequently approach property acquisition with multi-generational wealth horizons, such as securing properties to pass down to descendants.
Strategic Opportunities for Individual Investors
Changes in corporate capital allocation create distinct openings for smaller, agile operators. When large institutions concentrate their resources on specific asset classes or master-planned build-to-rent communities, they leave profitable niches unaddressed.
+———————————–+———————————–+
| Institutional Focus | Individual Investor Opportunity |
+———————————–+———————————–+
| Large-scale suburban development | Urban infill and ADU additions |
| Build-to-rent corporate models | Turnkey single-family rentals |
| All-cash bulk portfolio buys | Conventional financing plays |
+———————————–+———————————–+
By leveraging liberalized zoning to construct accessory dwelling units (ADUs) or converting single-family homes into compliant duplexes, independent participants can enhance local housing supply while capturing strong risk-adjusted returns. Furthermore, lower overall institutional market share ensures that private buyers using conventional financing are not constantly priced out by all-cash corporate giants.
Multifamily Market Resilience and Rental Fundamentals
Beyond single-family housing, the multifamily sector demonstrates strong operational metrics. Transaction volumes have rebounded from cyclical lows, accompanied by exceptionally high occupancy rates that rank among the highest nationwide.
Effective rental rates continue to outperform broader national benchmarks, supported by a projected slowdown in new unit completions. With developer caution leading to a significant drop in new apartment groundbreakings, supply constraints will likely sustain steady rent growth across key submarkets, ensuring favorable conditions for income-focused portfolios.
Navigating Seattle’s Evolving Real Estate Ecosystem
Ultimately, corporate capital represents only one variable in a multifaceted urban economy. While public discourse often emphasizes institutional dominance, empirical data demonstrates that local markets maintain one of the lowest corporate ownership shares among major metropolitan areas.
For owner-occupants, this translates to reduced competition from all-cash institutional buyers. For individual investors, it presents clear opportunities to capitalize on zoning changes, multifamily fundamentals, and underserved market segments.
To develop a personalized strategy that accounts for shifting institutional activity while identifying your best opportunities, schedule a consultation with SJA Property Management today. Our expert team delivers comprehensive market intelligence and professional management consulting to help you succeed in the Pacific Northwest property market.