Navigating the Modern American Housing Market: Why Buying a Home is So Complex Today
Over the past decade working directly in residential construction, real estate development, and property asset management, I have watched the American housing landscape undergo a profound structural transformation. From guiding first-time buyers through high-stakes bidding wars to consulting with commercial developers on regional housing shortages, one reality remains constant: the modern real estate market has never been more challenging to navigate.
Homeownership has historically served as the cornerstone of generational wealth creation in the United States, representing a vital milestone for families across the country. Yet, today’s prospective buyers face an intimidating convergence of high property values, shifting interest rate environments, and chronic inventory deficits. To truly understand why securing property feels so difficult, we have to look past the surface-level headlines and examine the macroeconomic trends, regional variances, and demographic shifts shaping the industry.
The Great American Real Estate Disparity: From Atherton to West Virginia
When analyzing the national housing market, averages can be deeply misleading. The United States housing sector is not a single monolith; rather, it is a mosaic of hyper-localized micro-economies with stark contrasts in pricing and accessibility.
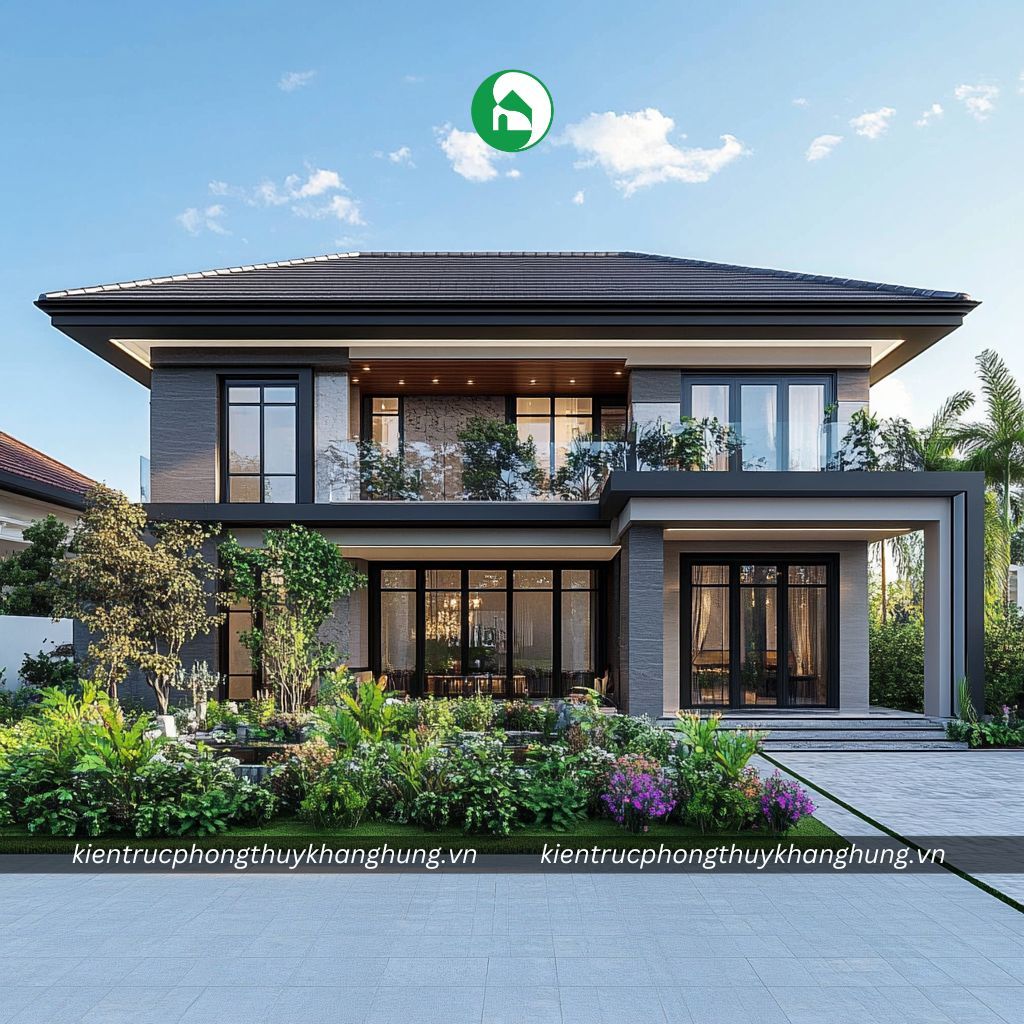
At the extreme high end, communities like Atherton, California, command median home listing prices approaching $8 million. This creates an exclusive barrier to entry accessible only to high-net-worth individuals. Conversely, states like West Virginia feature median home prices hovering around $140,000. Interestingly, this affordability correlates directly with higher regional participation: West Virginia boasts one of the highest homeownership rates in the nation at nearly 75%, whereas California sits closer to 55%.
Nationwide, roughly 65% of American households own their primary residence, with over a quarter of these properties valued above half a million dollars. This substantial equity stake underpins much of the middle class’s financial security. However, regional disparities dictate whether a young family can realistically transition from renting to owning.
Regional Spotlight: The Michigan Advantage and National Inventory Shortfalls
While coastal markets grab the financial headlines, states like Michigan showcase a much more balanced baseline. Michigan stands out as a national leader in housing tenure and stability, with ownership rates hovering above 70% and residents often remaining in their dwellings for decades.
The median price for a home in Michigan sits comfortably around $250,000, representing steady, manageable annual appreciation. Furthermore, buyers get significantly more space for their investment here: while the median square footage for a home nationwide sits around 1,800 square feet, Michigan homes average over 2,000 square feet. Nationally, newly constructed homes skew even larger—often exceeding 2,500 square feet—though the existing housing stock contains a vast footprint of smaller, more traditional footprints.
Across the United States, the total housing inventory counts nearly 150 million homes, with over 130 million currently occupied. Despite these massive figures, industry authorities like the National Association of Home Builders have warned for years that population growth projections and an aging housing stock point toward a persistent deficit.
Current estimates suggest the United States faces a cumulative shortfall of nearly 6 million available housing units. California alone accounts for an estimated 2 million of those missing homes, while New York trails with a deficit of nearly 1 million.
However, raw unit counts do not tell the whole story. Affordability dictates whether these properties solve the crisis. For instance, fast-growing markets like Fort Lauderdale, Florida, have experienced overbuilding in certain luxury segments, pushing median home prices past $500,000. Interestingly, market corrections there show up to 85% of homes selling below their initial listing price, proving that mismatched pricing can stall even active markets. Sustainable solutions require constructing homes precisely calibrated to the demographics actively trying to buy.
Macro Trends: Remote Work, Lock-In Effects, and Aging in Place
The post-pandemic economic landscape fundamentally altered how Americans view their living spaces. In the wake of COVID-19, a massive segment of the workforce discovered the viability of remote work, sparking a wave of geographic mobility.
Simultaneously, however, macroeconomic shifts created the “lock-in effect.” As mortgage interest rates rose from historic lows, millions of existing homeowners became financially tethered to favorable 30-year fixed-rate mortgages obtained years prior. Trading a 3% mortgage for a 7% mortgage made moving financially unfeasible for many, freezing housing mobility and keeping inventory artificially low.
We have also witnessed a fascinating shift in retirement trends. For decades, conventional wisdom assumed retirees would automatically migrate to warmer Southern climates for their golden years. Today, many older adults are choosing to stay put. Relocating often means leaving behind vital life anchors, including trusted physicians, places of worship, social circles, and extended family.
Rather than uprooting, older demographics are increasingly reinvesting in their properties. Homeowners frequently find it more cost-effective and emotionally rewarding to remodel their current dwellings—adding main-floor living spaces, zero-step entries, and smart accessibility features—to safely age in place rather than navigate a competitive buying market.
The Generational Divide and the Path Forward
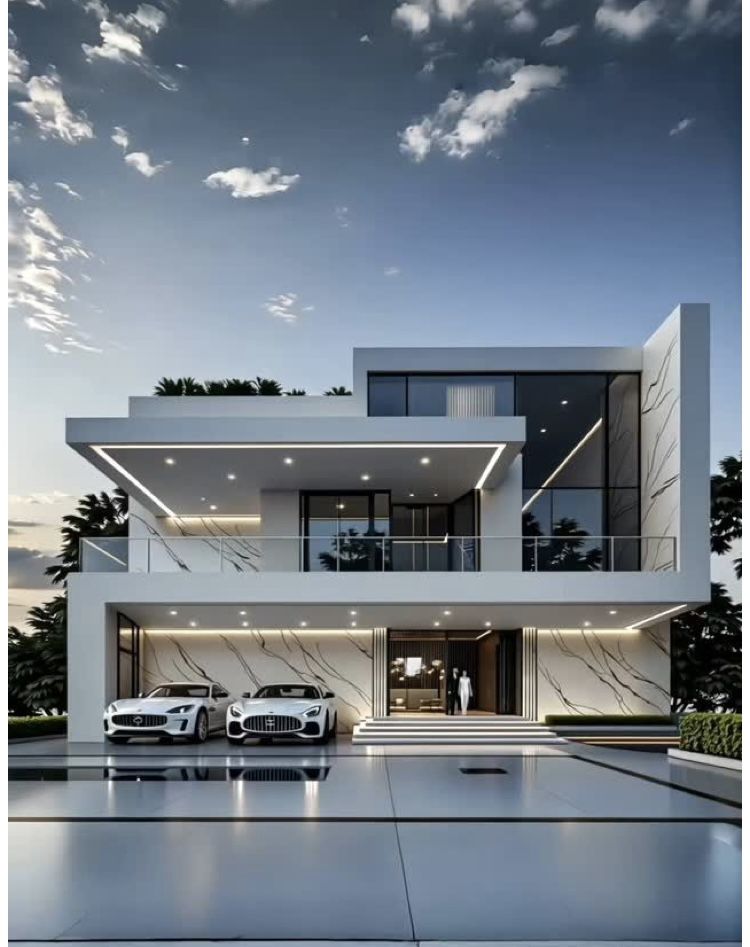
Perhaps the most pressing challenge in today’s real estate market is the widening generational gap in homeownership. While nearly 80% of adults over the age of 65 own their homes, that figure drops below 40% for young adults under the age of 35.
For millennials and Gen Z, achieving homeownership involves navigating a complex web of high development costs, limited land availability, restrictive zoning laws, and the high cost of borrowing money. Affordability is never a one-size-fits-all issue; it requires careful coordination between regional planners, municipal leaders, and skilled residential contractors.
Maintaining our existing housing stock while strategically expanding inventory in high-demand areas is essential for supporting the next generation of buyers. Whether you are planning a comprehensive home renovation to improve your current living space or evaluating your readiness to enter the real estate market, professional guidance makes all the difference.
If you are ready to take the next step toward optimizing your property or exploring your financing options in today’s evolving market, reach out to a trusted local real estate professional or qualified contractor today to schedule your initial consultation.