Decoding the American Housing Shortage: Why Real Estate is So Expensive and Scarce
Navigating the American residential real estate market over the past decade has felt less like a traditional financial milestone and more like scaling an insurmountable peak. Having spent over ten years advising prospective buyers, auditing structural inventory, and consulting on major developments across the country, I have watched the American housing shortage transition from an industry talking point into a full-scale socioeconomic crisis.
When clients ask why housing is so expensive and stubbornly hard to find, the answer is rarely tied to a single variable. Instead, it is a complex web of macroeconomic pressure, shifting generational demographics, interest rate handcuffs, and a severe structural deficit in residential construction.
The Macro View: Disparity Across the National Landscape
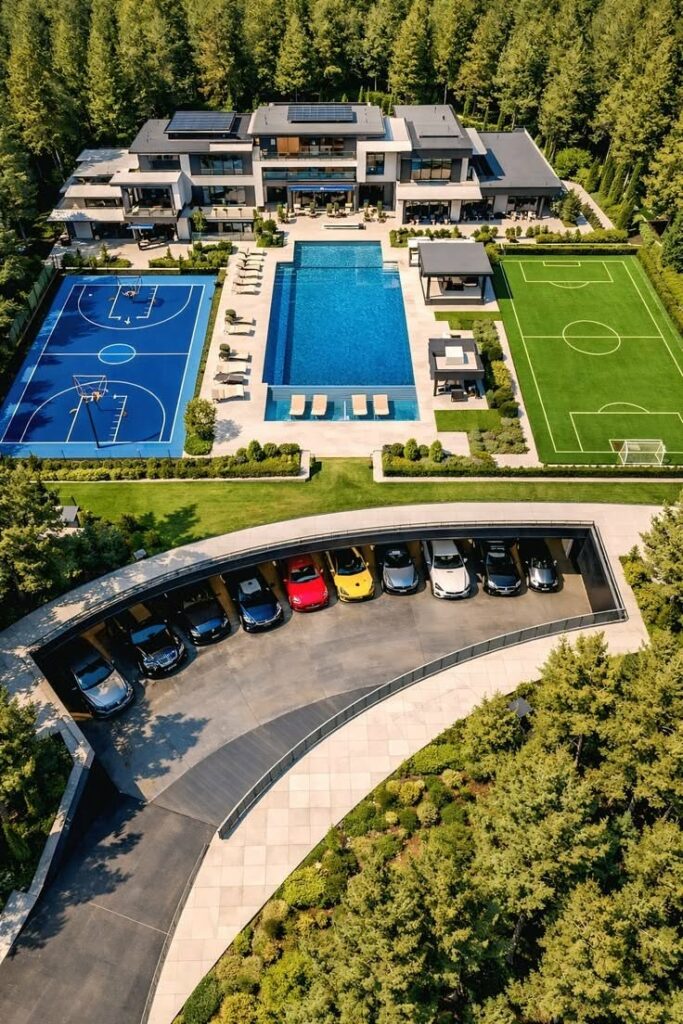
To understand the current crisis, we have to look at the stark geographical divides that define the U.S. property market. On one extreme, ultra-exclusive luxury enclaves like Atherton, California, boast median home listing prices approaching $8 million, pushing homeownership entirely out of reach for median-income earners. Conversely, states like West Virginia maintain median home values hovering around $140,000, which correlates directly with a staggering homeownership rate of nearly 75%—the highest in the country. California, by comparison, lags at roughly 55%.
Nationwide, roughly 65% of American households own their homes. For generations, this asset class has served as the bedrock of generational wealth accumulation. More than a quarter of all owner-occupied properties across the United States are currently valued above half a million dollars, representing a massive portion of private equity.
Regional anomalies also reveal fascinating insights into square footage and value. While the national median home size floats around 1,800 square feet, states like Michigan showcase a healthier baseline, where the median size exceeds 2,000 square feet and homeownership rates consistently hover above 70%. In Michigan, median home prices sit near $250,000, demonstrating that regional market health allows residents to stay anchored in their properties for decades, unlike hyper-transitory coastal corridors.
The Core Problem: The Multi-Million Unit Housing Shortage
The root cause of perpetual price inflation is simple economics: severe under-supply. The United States currently contains roughly 150 million housing units, with over 130 million actively occupied. However, industry analytics from institutions like the National Association of Home Builders have warned for years that steady population growth paired with an aging, obsolete housing stock would trigger a catastrophic supply crunch.
Today, national estimates indicate a structural shortfall of nearly 6 million available homes. The heaviest deficits are concentrated in high-demand economic engines:
California: Facing an estimated deficit of approximately 2 million homes.
New York: Struggling with a nearly 1 million unit deficit.
These massive shortages distort pricing mechanics, but local markets can behave counterintuitively. For instance, cities like Fort Lauderdale, Florida, have experienced aggressive overbuilding phases in specific luxury sectors, pushing median prices past $500,000. Interestingly, market data indicates that up to 85% of homes sold in those specific pockets eventually closed below listing price, proving that raw inventory numbers alone do not solve affordability if the housing stock does not match the demographic’s actual purchasing power.
The Lockdown Effect and the Mortgage Rate Trap
Two major historical catalysts transformed buyer behavior over the past several years. First, the widespread normalization of remote work during the COVID-19 pandemic caused millions of workers to reevaluate their living spaces, igniting a suburban and rural migration frenzy.
Second, as the Federal Reserve moved aggressively to combat inflation, mortgage rates spiked from historic lows. This created the infamous “lock-in effect.” Millions of existing homeowners who secured ultra-low 30-year fixed-rate mortgages in the 2% to 3% range became financially trapped in place. Walking away from those rates to purchase a new home at double the interest rate makes zero financial sense for the average household, effectively freezing residential mobility.
Compounding this is a fascinating shift in older demographics. For decades, conventional wisdom assumed retirees would automatically flee to warmer southern states. Instead, many aging adults realized that relocating meant abandoning crucial life anchors—trusted local physicians, lifelong social networks, neighborhood hubs, and nearby family support systems.
Consequently, older U.S. adults are choosing to “age in place.” Rather than selling, they are reinvesting capital into home renovations, universal design upgrades, and safety retrofits. Financial analysts note that remodeling an existing home often yields a far better return on investment than buying into an inflated market with steep transaction and financing costs.
The Generational Divide and Affordability Barriers
This stagnation has created a profound age disparity in the American housing market. Today, nearly 80% of adults over the age of 65 own their homes. In stark contrast, homeownership rates for young adults under the age of 35 sit below 40%.
Lower fixed-rate mortgage money and potential monetary easing will undoubtedly help bridge this gap, but financial relief alone is insufficient. The market desperately needs a massive influx of new inventory.
As an industry consultant, I continually remind stakeholders that affordability is never a one-size-fits-all issue. A complex cocktail of strict land-use regulations, protracted zoning approvals, high municipal development fees, skilled labor shortages, and the high cost of construction financing conspires to limit mobility for millennials eager to enter the market.
Moving Forward: Solutions for Sustainable Growth
Solving this crisis requires a coordinated, multi-pronged approach between municipal governments, developers, and seasoned industry professionals. We must streamline zoning laws to encourage missing-middle housing, incentivize sustainable infill construction, and prioritize building homes that align with the actual income demographics of first-time buyers.
Whether you are looking to audit your current property’s equity, plan a major energy-efficient renovation to age in place, or strategically evaluate your options in today’s shifting market, professional guidance is your greatest asset.
Are you planning to buy, sell, or remodel your home this year and want a professional market assessment tailored to your local region? Reach out today to schedule a consultation with our expert team and take the next step toward securing your housing future.